Get Indexology® Blog updates via email.

In This List

Introducing the S&P/BMV IPC Futures Indices: A Futures-Based View of the Mexican Equity Market

Poll Position: Performance of the S&P MidCap 400 around Mid-Term Elections

The Case for Indexing Cryptocurrencies

Look Again, It’s Coal Outside

Greek Myths and Icelandic Sagas: Reclassifications in the Global Market Library

Introducing the S&P/BMV IPC Futures Indices: A Futures-Based View of the Mexican Equity Market

Contributor Image
Eduardo Olazabal

Associate Director, Global Exchange Indices

S&P Dow Jones Indices

Introduction

The S&P/BMV IPC is Mexico’s flagship equity index, and around it sits a growing ecosystem of investable products, including futures listed on MexDer and CME.

The S&P/BMV IPC Futures Series was launched to serve that market, tracking a rolling long position in IPC futures rather than the underlying shares and published in price, excess and total return versions. It complements the S&P/BMV IPC rather than replacing it: a futures position carries a roll and earns no dividends, so the two indices measure different things by design.

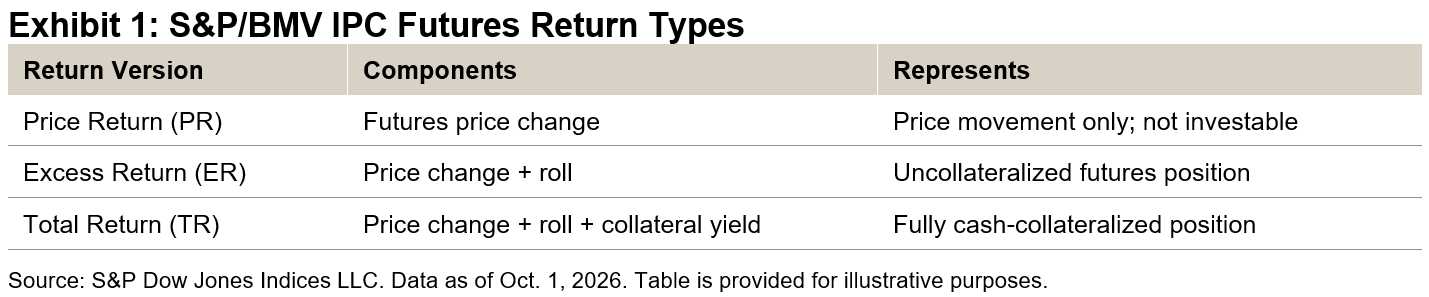
Understanding the S&P/BMV IPC Futures Return Types: Why Performance Can Differ

A futures contract is not the same as owning the shares it tracks. Contracts expire, so maintaining continuity means rolling from on contract into the next, which carries a cost or a benefit. Futures also require only a margin deposit rather than the full amount, so investors decide how much cash to hold alongside the position.

These two elements—the roll and future prices—are part of the differences between the return types. The spot version reflects the change in the futures price alone. The excess return version adds the roll. The total return version adds to the interest earned on cash held as collateral. Each return type measures something different, and each suits a different purpose.
How Does the S&P/BMV Futures Series Differ from the S&P/BMV IPC?

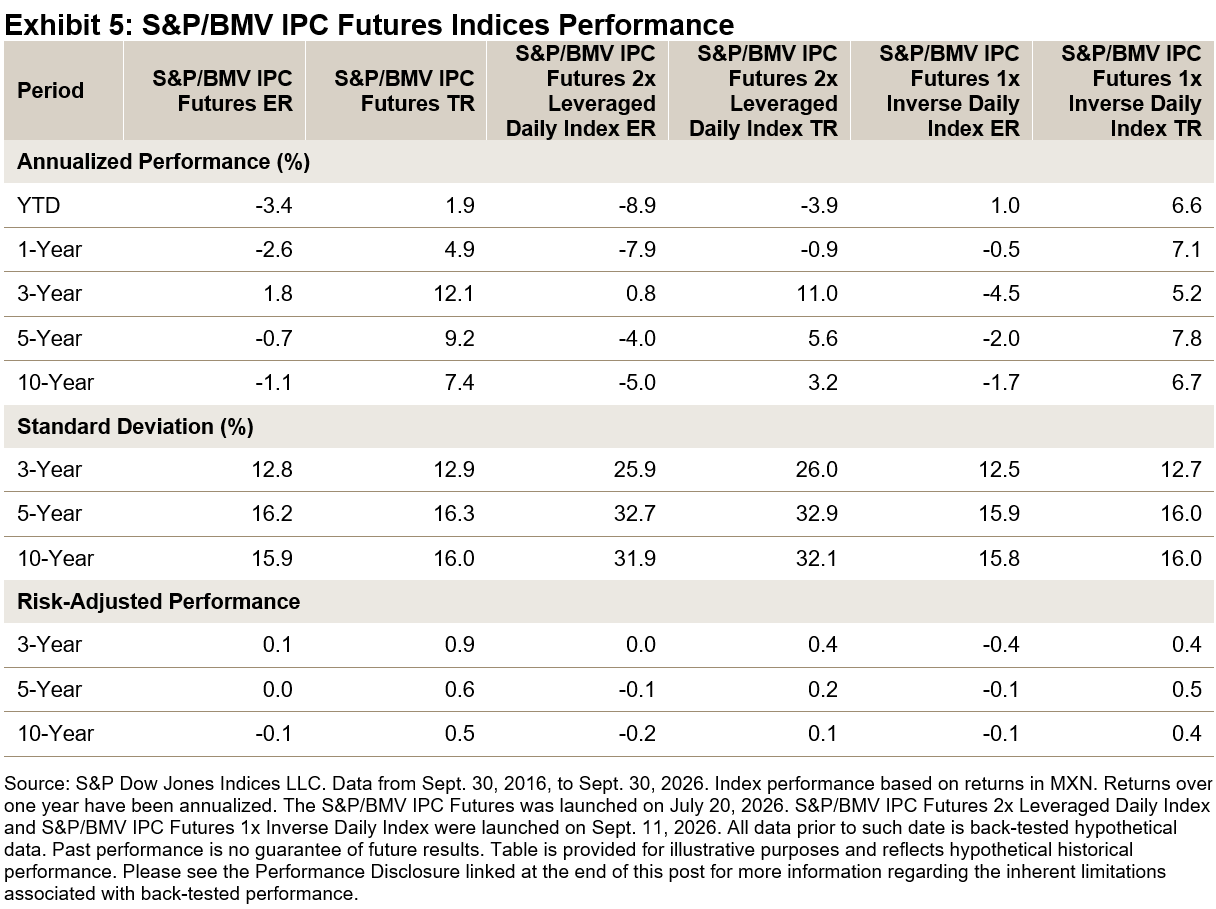
The S&P/BMV IPC Futures measures the S&P/BMV IPC as held through contracts rather than shares. The S&P/BMV IPC has tracked the S&P/BMV IPC Futures PR closely—3.1% versus 3.2% annualized over ten years—confirming the contracts priced the index faithfully. However, this version is not investable, since maintaining a futures position requires periodic rolling. The S&P/BMV IPC Futures ER and S&P/BMV IPC Futures TR account for that cost and for the treatment of cash held against the position.
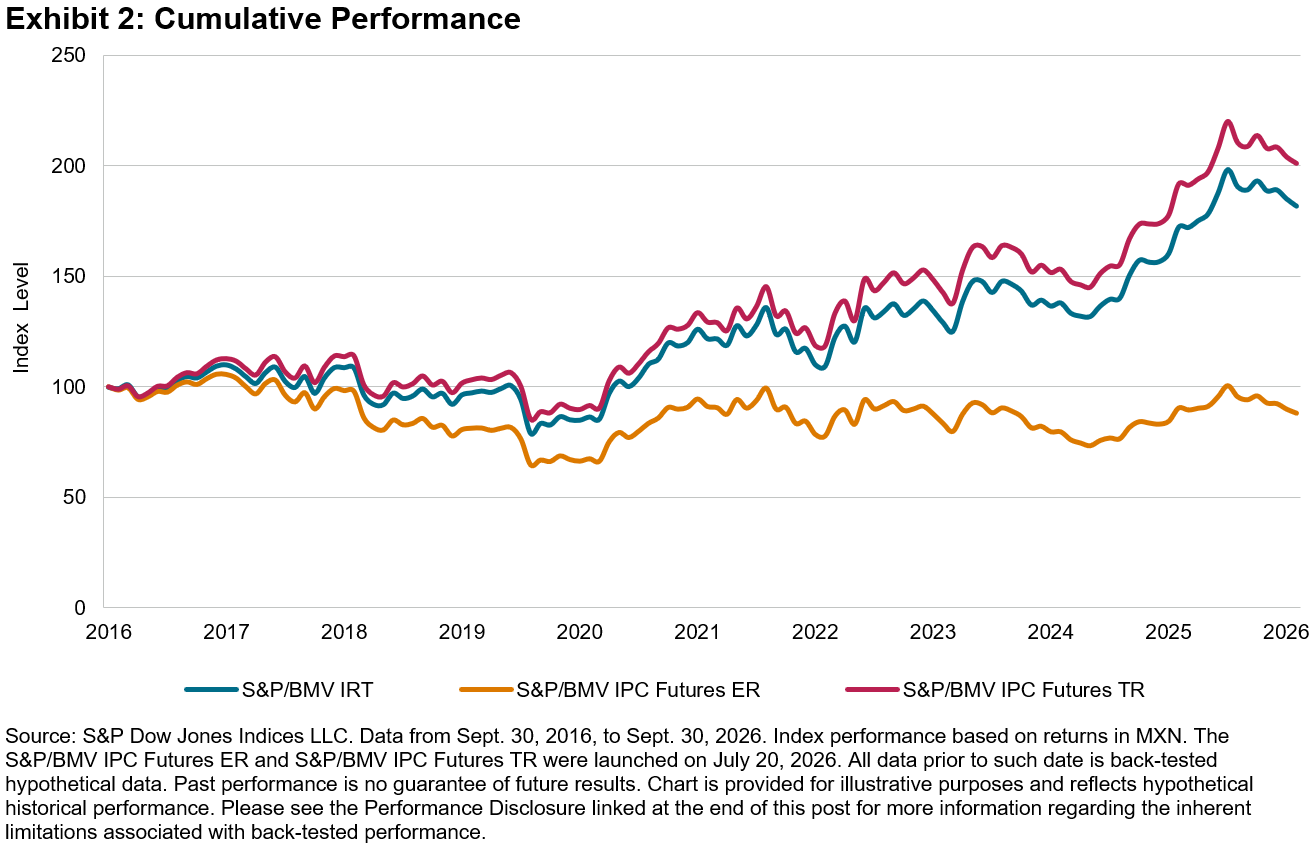
Each time an expiring contract is replaced, the next one is priced to reflect the cost of financing the exposure less the dividends foregone. The S&P/BMV IPC Futures ER reflects this: it sits 4.3% a year below the spot version, which is the cost of the roll. The S&P/BMV IPC Futures TR then adds the interest earned on cash held as collateral, 8.5% a year, lifting it above the S&P/BMV IRT.

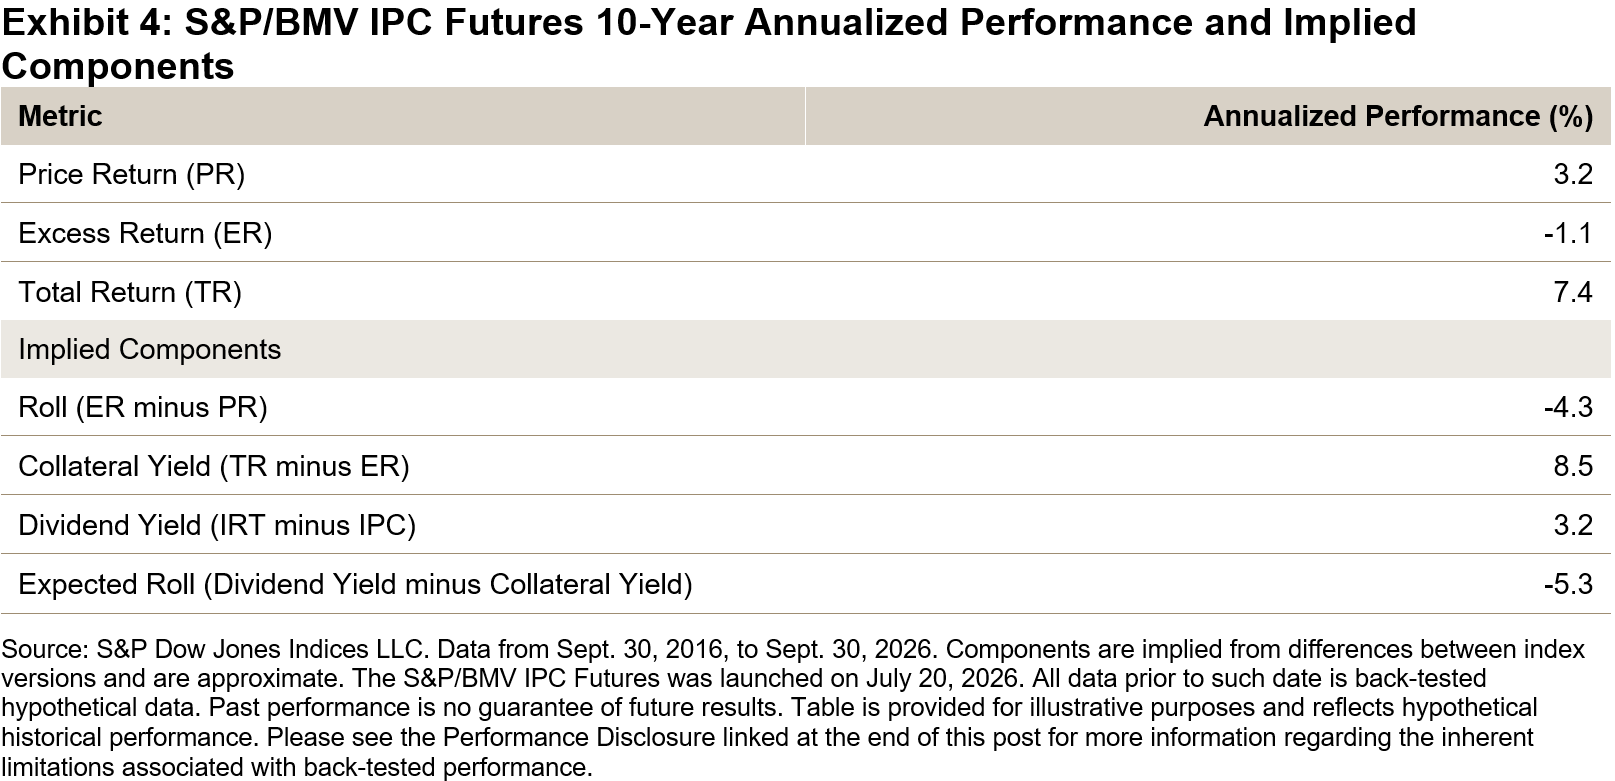
The size of the roll is worth noting. Futures are priced to reflect the cost of financing the exposure less the dividends foregone, so with a collateral yield of 8.5% and a dividend yield of 3.2%—both implied by the gaps in Exhibit 3—the roll would be expected to cost around 5.3% a year. It cost 4.3%.
Leveraged and Inverse Versions Are Also Available

The series extends to the S&P/BMV IPC Futures 2x Leveraged Daily Index and S&P/BMV IPC Futures 1x Inverse Daily Index, built from the same contracts and reset daily.

Because the multiple is reset each day, returns compound from one day to the next. Over longer periods, the result can differ substantially from the stated multiple, and the difference grows as volatility rises. Leveraged and inverse indices are therefore typically used for short-term hedging and directional positioning rather than long-term holding.

The 10-year figures show this. Twice the 1x ER of -1.1% would be -2.2%; however, the S&P/BMV IPC Futures 2x Leveraged Daily Index ER fell 5.0% annualized, with volatility roughly doubling from 15.9% to 31.9%. For the S&P/BMV IPC Futures 1x Inverse Daily Index, a -1x multiple would imply +1.1%, while the S&P/BMV IPC Futures 1x Inverse Daily Index ER fell 1.7%.

The collateral yield does not scale either—8.5% annualized for the 1x version and 8.2% for the 2x—because it is earned on the capital invested rather than the exposure taken.

The roll also works in the opposite direction for a short position, which receives it rather than paying it. That cushioned the inverse ER over 10 years in which prices rose, and left its TR of 6.7% close to the 7.4% of the long TR.
Conclusion

The S&P/BMV IPC Futures Indices expand the toolkit for analyzing Mexican equities by recognizing that, when exposure is held through contracts, measured performance depends on the roll and the funding assumption applied. By viewing the futures versions alongside the S&P/BMV IPC and S&P/BMV IRT, market participants can separate price movement from the roll and the collateral yield.

The S&P/BMV IPC Futures 2x Leveraged Daily Index and S&P/BMV IPC Futures 1x Inverse Daily Index extend the same framework to daily-reset exposures, where compounding means longer-period performance can differ substantially from the stated multiple.

The posts on this blog are opinions, not advice. Please read our Disclaimers.
Poll Position: Performance of the S&P MidCap 400 around Mid-Term Elections

Contributor Image
Florence Chapman

Senior Analyst, U.S. Equities

S&P Dow Jones Indices

The S&P 500®, the S&P MidCap 400® and the S&P SmallCap 600® measure the performance of the large-, mid- and small-cap segments of the U.S. equity market, respectively. When considered together, they provide broad coverage of the U.S. equity market; however, each index represents a distinct segment with a unique constituent profile, sector composition and risk/performance characteristics.

Large caps typically offer scale and global reach, small caps can be associated with earlier-stage company growth and mid caps tend to occupy the space in between. Often overlooked, mid-cap companies can be established enough to offer operating scale and access to capital, yet still early enough in development for growth to matter.1

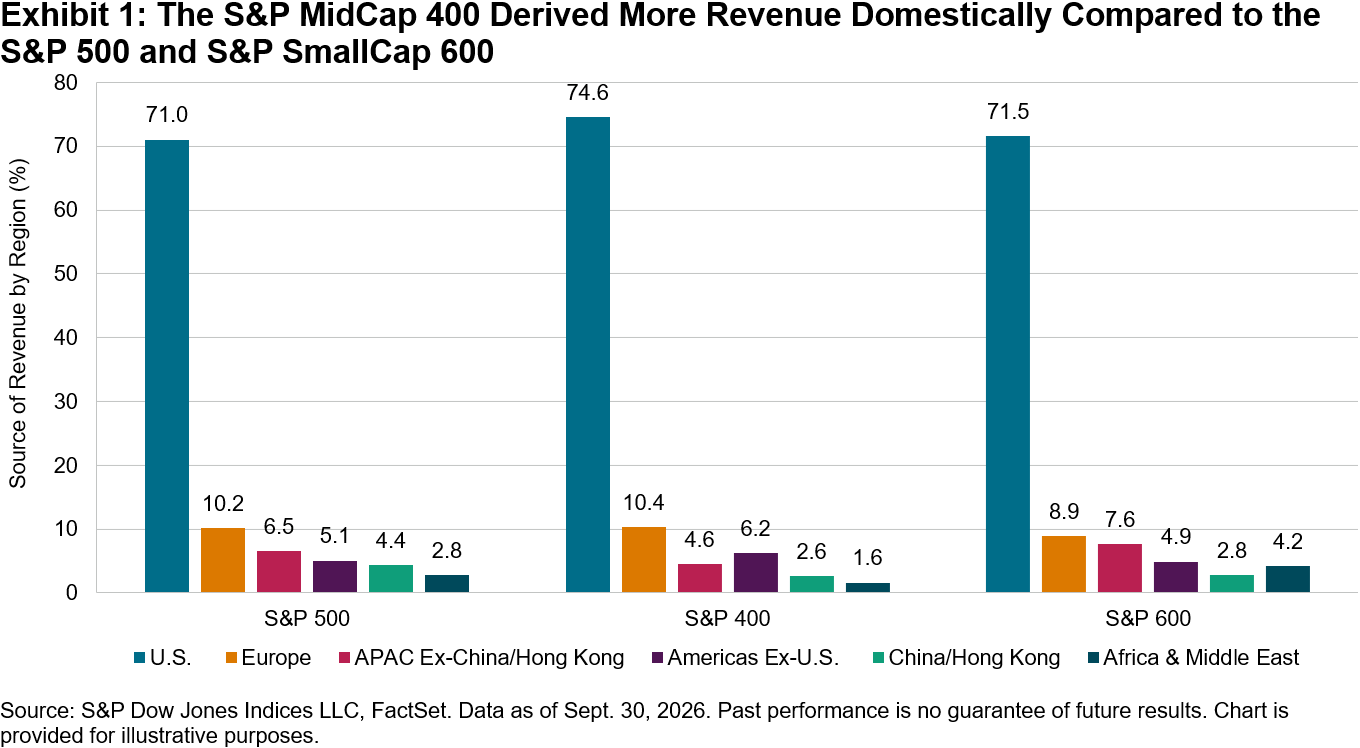
One example of how differing constituent profiles can translate into distinct characteristics is geographic revenue. Exhibit 1 shows the revenue breakdown by geography for the S&P 500, S&P 400® and S&P 600® as of the end of September 2026. On a sales-weighted basis, the S&P 400 had the highest domestic revenue exposure of the three indices, with 74.6% sourced from the U.S., compared with 71.0% and 71.5% for the S&P 500 and S&P 600, respectively. This higher domestic revenue exposure reflects, in part, the S&P MidCap 400’s sector composition, with relatively greater weights in more domestically oriented sectors such as Industrials and Real Estate.2

Differences in index characteristics can be informative when market attention shifts between global and domestic drivers. One historical lens through which to examine this dynamic may be the U.S. mid-term elections, which are held every four years, midway through a presidential term.3 Mid-term elections can coincide with a shift from pre-election uncertainty toward changing expectations for domestic policy and the U.S. economic outlook.

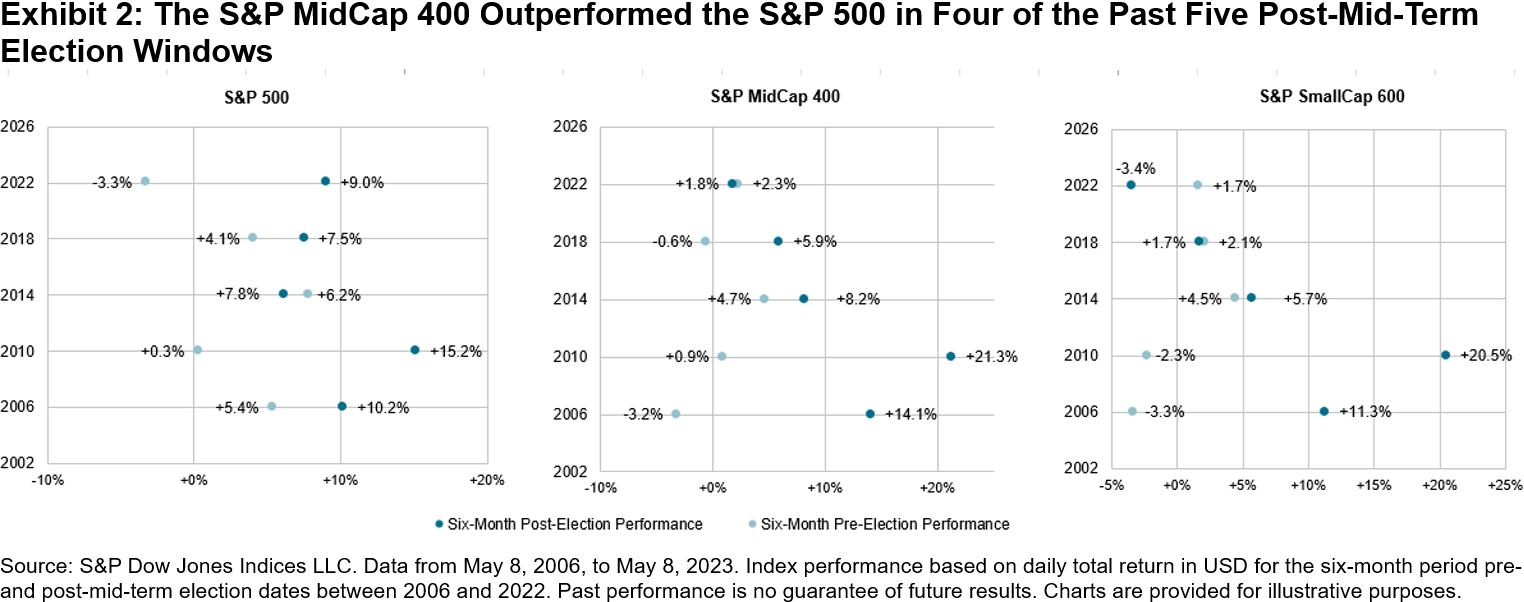
Exhibit 2 compares the performance of the S&P MidCap 400 with that of the S&P 500 and S&P SmallCap 600 over the six-month period before and after each of the five U.S. mid-term elections since 2006.

The S&P 400 outperformed the S&P 500 in four of the past five six-month periods following the mid-term elections. The mid-cap benchmark also outperformed the S&P SmallCap 600 in three of these periods. Across the five election cycles examined, the post-election performance ranged from 1.8% to 21.3% for the S&P 400, compared with -3.4% to 20.5% for the S&P 600 and 6.2% to 15.2% for the S&P 500. While the magnitude of performance varied from one cycle to the next, mid caps were strong performers in most of the post-election windows examined. While the drivers of performance varied across market cycles, these results highlight how differences in constituent profile, sector composition and economic sensitivity can contribute to distinct outcomes across market-cap segments.

More notably, perhaps, Exhibit 2 also shows the change in performance on either side of the election date. In four of the five cycles, mid caps posted stronger performance in the six months following the election than in the six months prior. The improvement ranged from 3.5% in 2014, to more than 20% in both 2006 and 2010, with 2022 representing the only exception. Although stronger post-election performance was also observed in four and three of the five cycles for the large and small caps, respectively, the increase between the pre- and post-election periods was the largest for the S&P MidCap 400.

Applying the same analysis to equivalent dates in non-election years4 showed a weaker relationship between pre- and post-period performance, suggesting that the historical post-mid-term pattern may not be explained by calendar timing alone. One possible explanation is that market participants may have historicaly reasessed the domestic outlook more positively following mid-term elections.

Conclusion

Historical index performance around mid-term elections provides one example of how the distinct characteristics of the S&P MidCap 400 have translated into different outcomes from its large- and small-cap counterparts. While these observations do not establish a persistent relationship, they illustrate how differences in constituent profile, sector composition and economic sensitivity have impacted performance across market-cap segments. More broadly, these differing characteristics can reinforce the case for looking beyond large caps when considering the breadth of U.S. equities.

1 Explore these characteristics in greater detail in the S&P MidCap 400 Brochure.

For further reading, see Bellucci, Louis and Hamish Preston, “The S&P MidCap 400: Outperformance and Potential Application,” S&P Dow Jones Indices, July 9, 2019.

2 For current detail on sector weights, see the S&P MidCap 400 webpage.

3 For a broader analysis on the relationship between election cycles and index performance, see Hyman, Lucas, “Ballots and Benchmarks: How Elections Shake Markets around the World,” S&P Dow Jones Indices, Aug. 31, 2026.

4 Analysis based on equivalent mid-term calendar dates in the following years: 2007, 2011, 2015, 2019 and 2023.

The posts on this blog are opinions, not advice. Please read our Disclaimers.
The Case for Indexing Cryptocurrencies

Contributor Image
Marco Zhang

Quantitative Analyst, Index Investment Strategy

S&P Dow Jones Indices

While indexing has been established as a core building block in traditional asset classes such as U.S. equities,1 digital assets continue to be viewed largely through the lens of individual tokens, particularly Bitcoin. Seventeen years after Bitcoin’s genesis block, the market now includes increasing institutional participation, regulated exchanges, spot ETFs and an ecosystem that extends well beyond Bitcoin. In this blog, we are taking a look into a diversified index approach for cryptocurrencies.

Why Does Indexing Work?

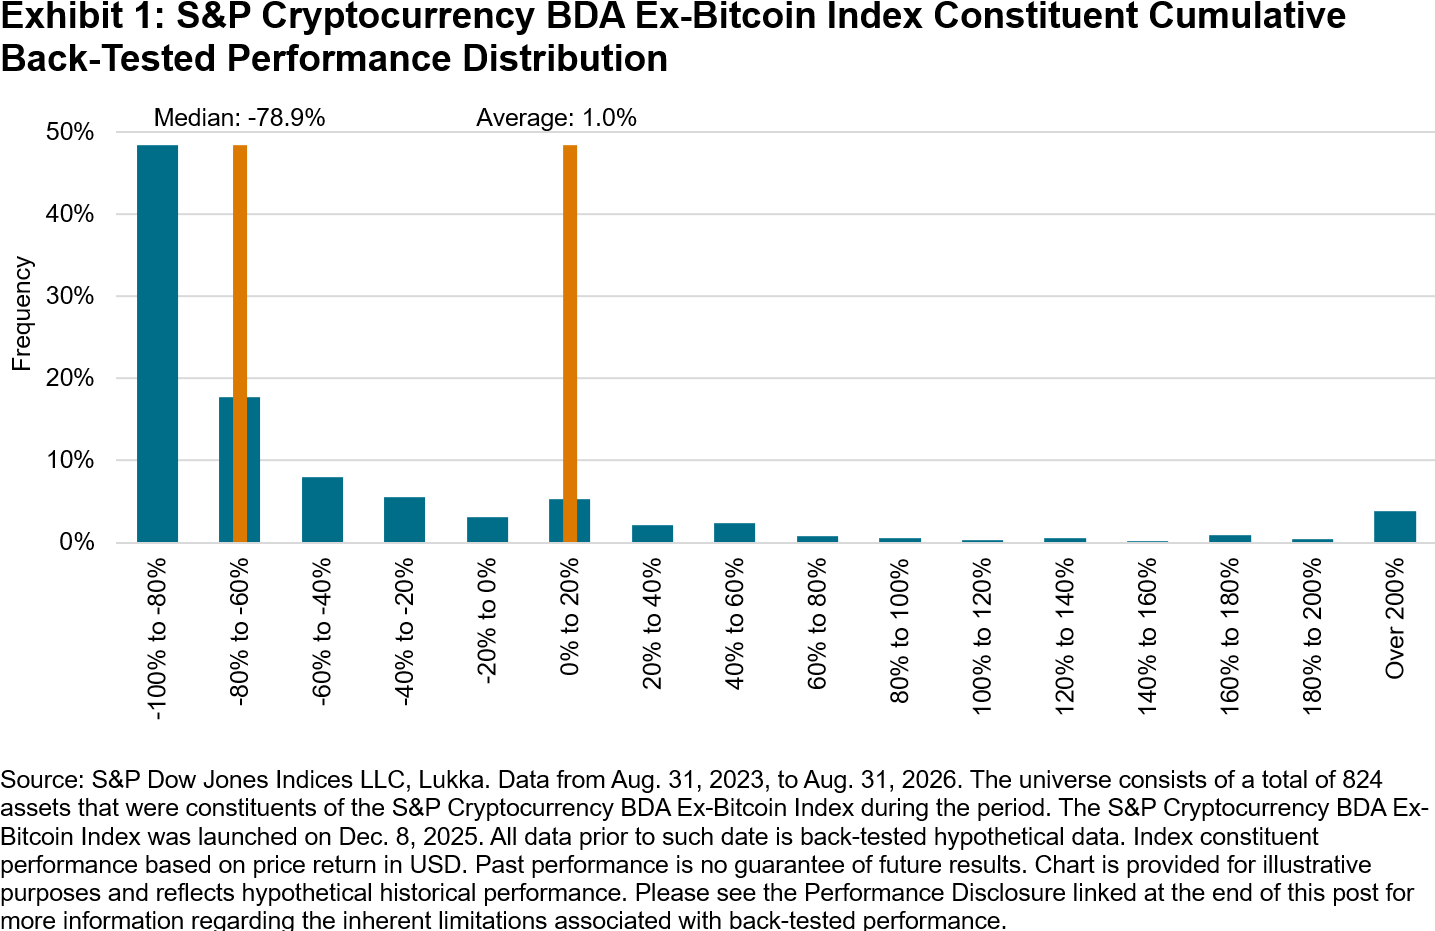
A key context for understanding indexing can be found in the performance distribution of the underlying assets. Exhibit 1 illustrates the distribution of cumulative performance for the constituents of the S&P Cryptocurrency Broad Digital Asset (BDA) Ex-Bitcoin Index over the three-year period ending Aug. 31, 2026. Outside of Bitcoin, cryptocurrencies had a median cumulative performance of -78.9%, compared with an average of 1.0%. A small number of tokens posted outsized gains of over 200%, lifting the average well above the median. Only 16% of constituents outperformed the average, while nearly half lost over 80% of their value. This positive skew in cryptocurrency performance generally held true over both the short and long term, similar to what we have observed in stock performance.2

In other words, successful coin selection depended on identifying a relatively small number of exceptional performers from a much larger universe of constituents. That is a difficult task. A diversified index approach, by contrast, aims to widen the focus beyond any single cryptocurrency and maintain representation across the opportunity set that drives market performance. Over the same period shown in Exhibit 1, the S&P Cryptocurrency BDA Ex-Bitcoin Index gained 37.1%, leaving just 10% of constituents above the index performance.

Diversification beyond Bitcoin

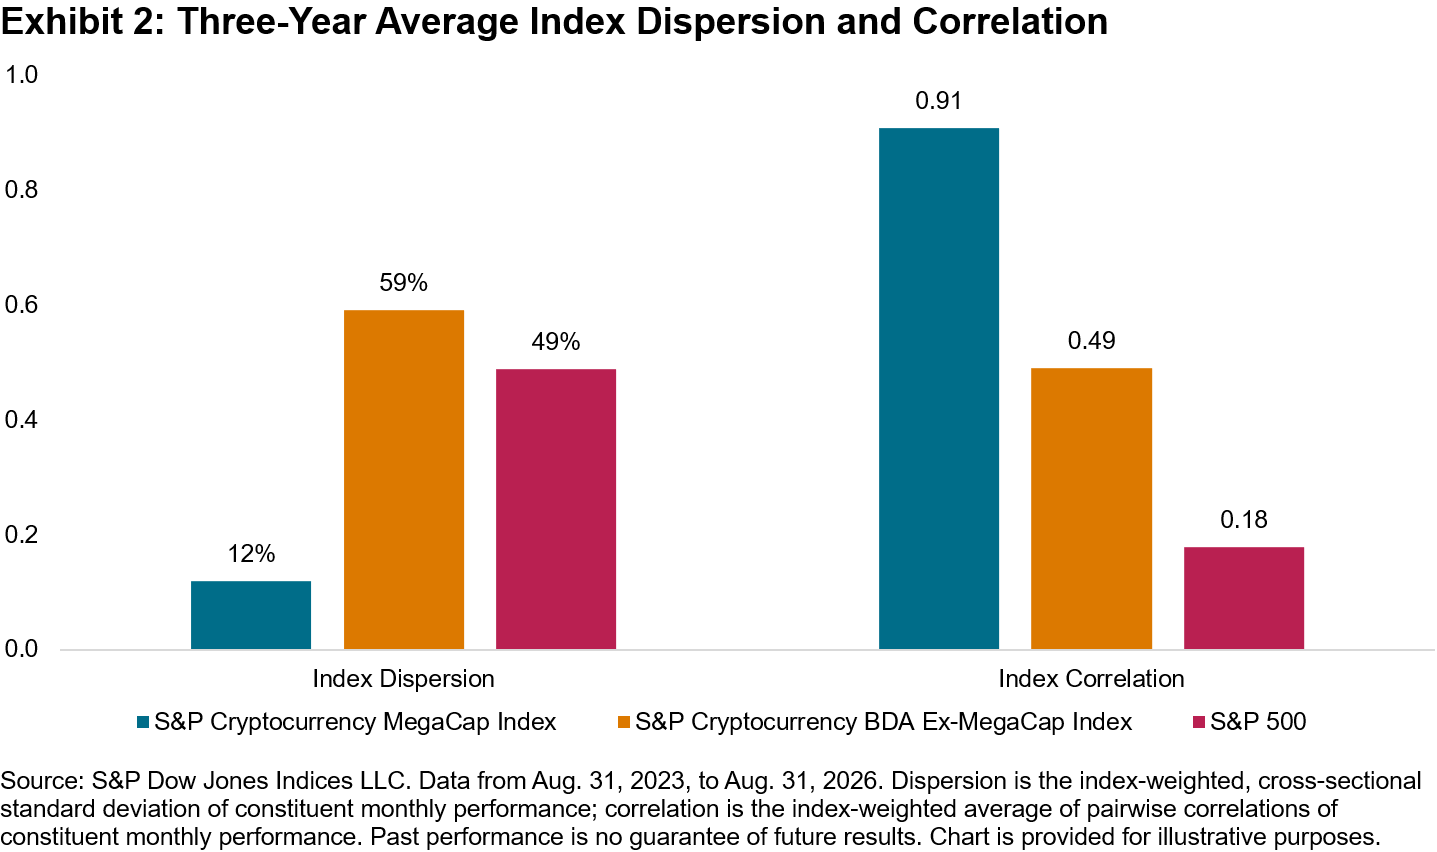
Although cryptocurrencies have long been dominated by Bitcoin and Ether, diversification opportunities did exist beyond these mega caps. As shown in Exhibit 2, the S&P Cryptocurrency BDA Ex-MegaCap Index exhibited considerably higher dispersion and lower correlation among constituents than the S&P Cryptocurrency MegaCap Index over the three-year period ending Aug. 31, 2026. The broader universe contained a wider range of performance drivers than Bitcoin and Ether alone.

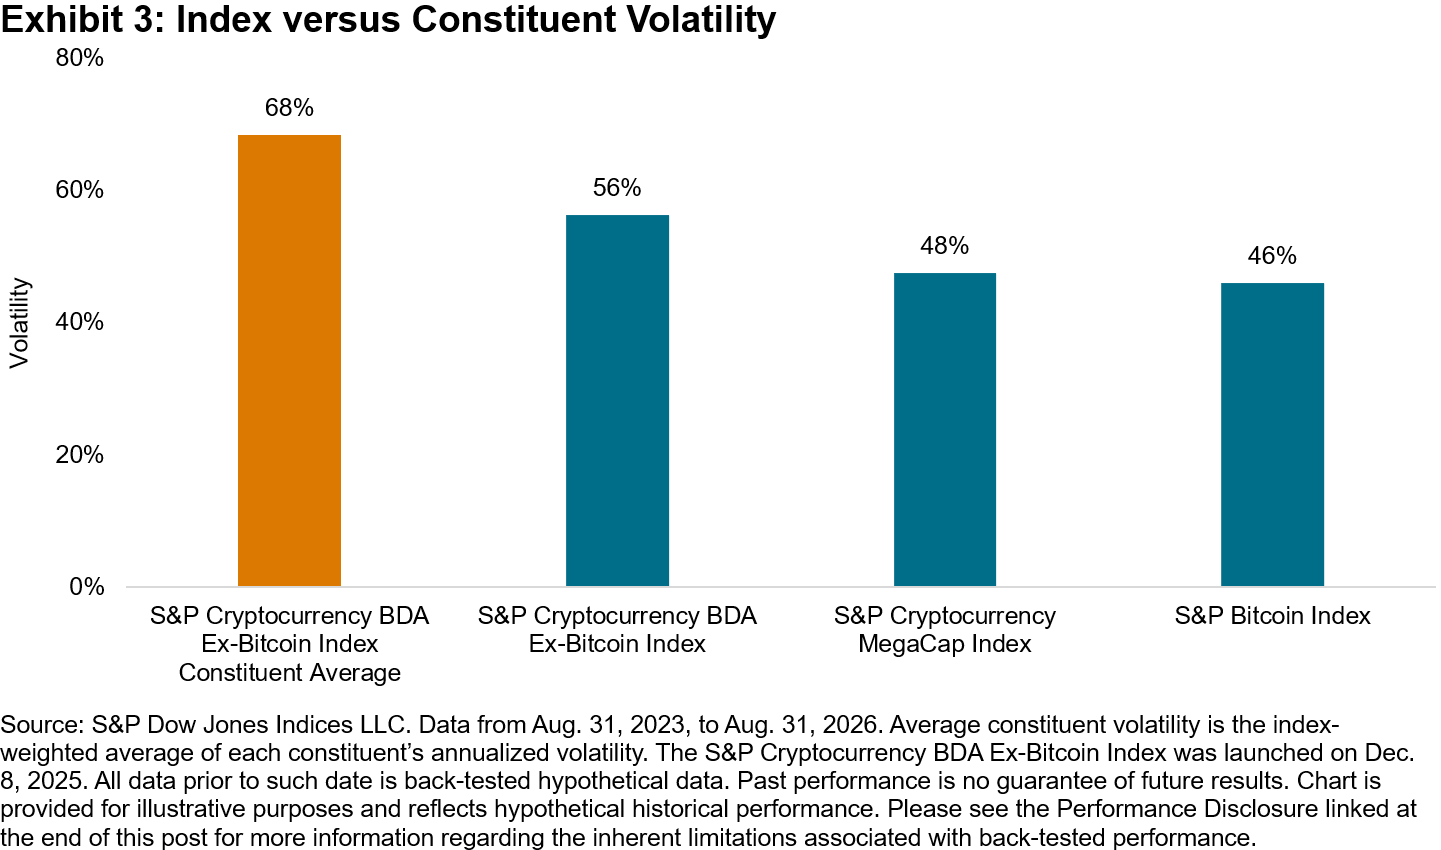
Diversification can reduce volatility when the underlying assets do not move in lockstep. As shown in Exhibit 3, the volatility of the S&P Cryptocurrency BDA Ex-Bitcoin Index was considerably lower than the average volatility of its constituents over the three-year period ending Aug. 31, 2026. However, the index remained more volatile than the S&P Bitcoin Index over the same period, reflecting the higher risk profile of the outside-of-Bitcoin universe.

Exploring Indexing Approaches

While market capitalization weighting is among the most common approaches to indexing, there could be many different ways to construct cryptocurrency indices.3 The S&P Pantera Digital Asset Index, for example, uses a systematic approach that applies fundamental screens for positive protocol revenue and excludes Bitcoin entirely.

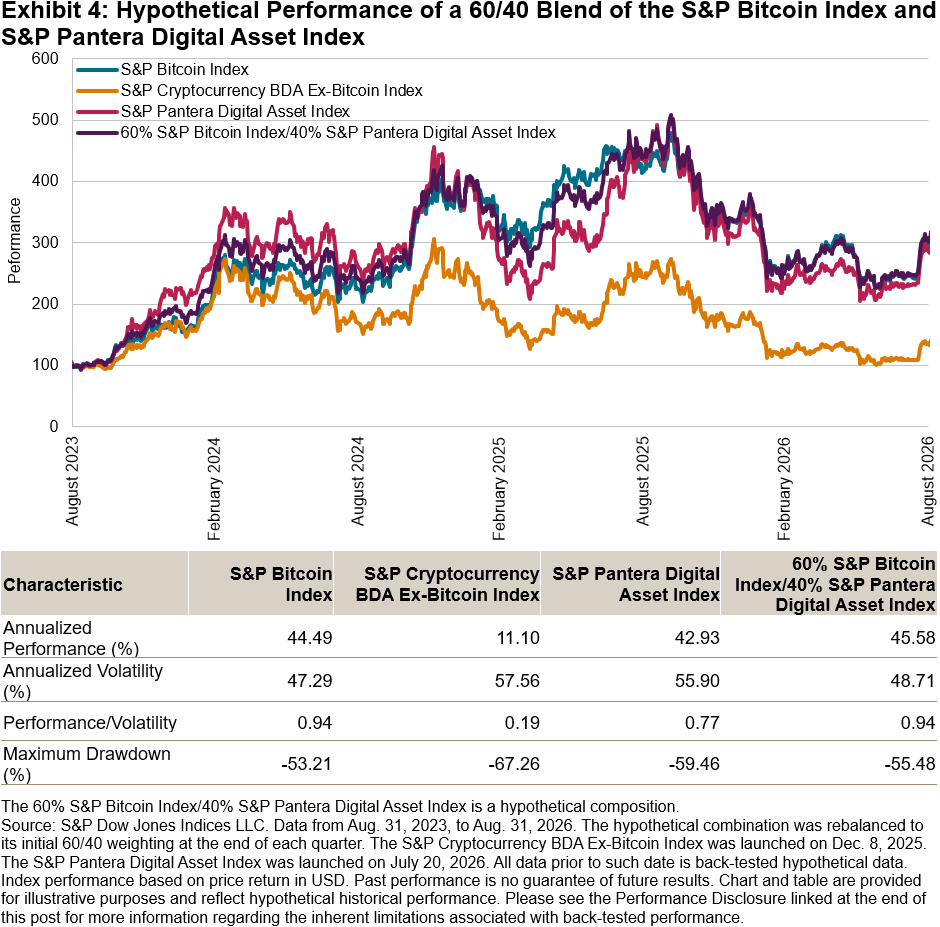
Exhibit 4 illustrates the performance of the S&P Pantera Digital Asset Index and a hypothetical blend of 60% S&P Bitcoin Index and 40% S&P Pantera Digital Asset Index, a combination that broadly mirrors Bitcoin’s share of the cryptocurrency market.

During the three-year back-tested period ending Aug. 31, 2026, the S&P Pantera Digital Asset Index outperformed the S&P Cryptocurrency BDA Ex-Bitcoin Index on both absolute and risk-adjusted bases. More interestingly, the 60/40 index blend resulted in higher absolute performance than the S&P Bitcoin Index and comparable risk-adjusted performance, while experiencing slightly larger drawdowns. These results suggest that a “barbell” approach combining Bitcoin with a diversified index that excludes Bitcoin demonstrated a balance between performance potential and risk exposure.

The potential for indexing cryptocurrencies may rest on lessons from equities. With positively skewed individual asset performance, identifying outperformers in advance has proven statistically difficult. As institutional adoption broadens and the digital asset ecosystem matures, indexing may play a similar role in cryptocurrencies to the one it has long played in equities by providing a transparent, diversified and systematic approach to the market.

1 Approximately USD 16 trillion was indexed to the S&P 500 as of December 2025. See “S&P Dow Jones Indices Annual Survey of Assets” for further details.

2 For the skew in equity returns, see Ganti, Anu R. and Craig J. Lazzara, “Shooting the Messenger,” S&P Dow Jones Indices LLC, Nov. 22, 2022.

3 See the Digital Assets page for the full list of digital asset indices offered by S&P Dow Jones Indices. In addition, S&P Dow Jones Indices recently announced a partnership with Kaiko to launch the S&P Kaiko Digital Asset Indices suite. See the Kaiko website for information.

The posts on this blog are opinions, not advice. Please read our Disclaimers.
Look Again, It’s Coal Outside

Contributor Image
Vidushan Ragukaran

Director, Global Equities & Thematic Indices

S&P Dow Jones Indices

Lumps of coal are typically reserved for the Christmas stocking of the worst-behaved children. With the holiday season approaching, many will be hoping instead for something a little shinier and more refined.

The S&P Global Mining Reduced Coal Index follows a similar philosophy. Start with a universe of mining-related companies. Focus on those with meaningful involvement in metals and minerals. Remove companies with significant coal exposure. What remains is a more targeted set of businesses involved in extracting some of the resources shaping the economy, from gold and silver to copper, lithium and uranium.

Reinforcing Positive Behavior

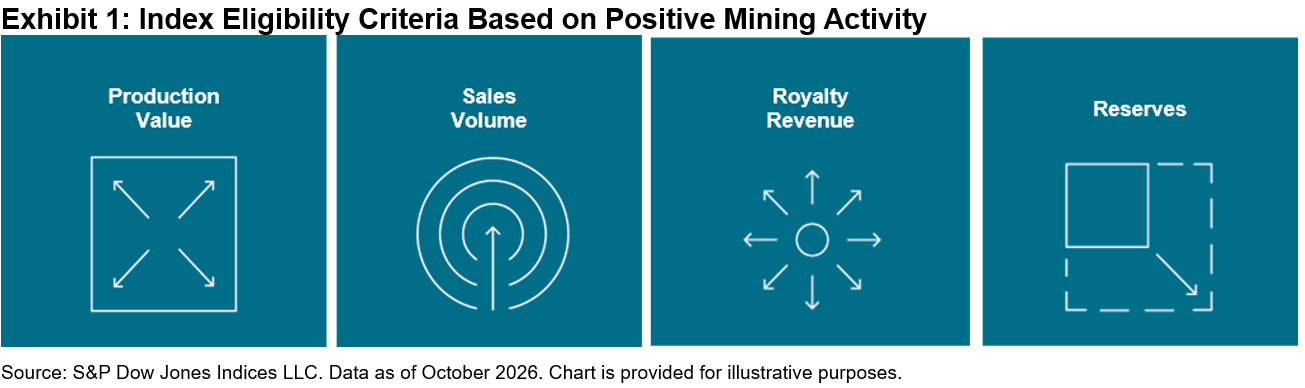
The starting point is the S&P Global Mining Index, which leverages commodity-level intelligence from S&P Global Energy (formerly S&P Global Commodity Insights). Eligibility is determined through evidence of positive global production value, sales volume, royalty revenue or reserves linked to a defined basket of mined commodities.1

This activity screen acts as a quality filter, recognizing multiple forms of meaningful participation (see Exhibit 1). Companies generating production value or sales volumes are actively participating in resource extraction today, while royalty companies provide financing and exposure to the underlying economics of mining projects. Reserves, meanwhile, provide evidence of resource ownership and future production potential. Collectively, these measures focus the index on companies with demonstrable involvement in the mining value chain rather than speculative exploration activity.

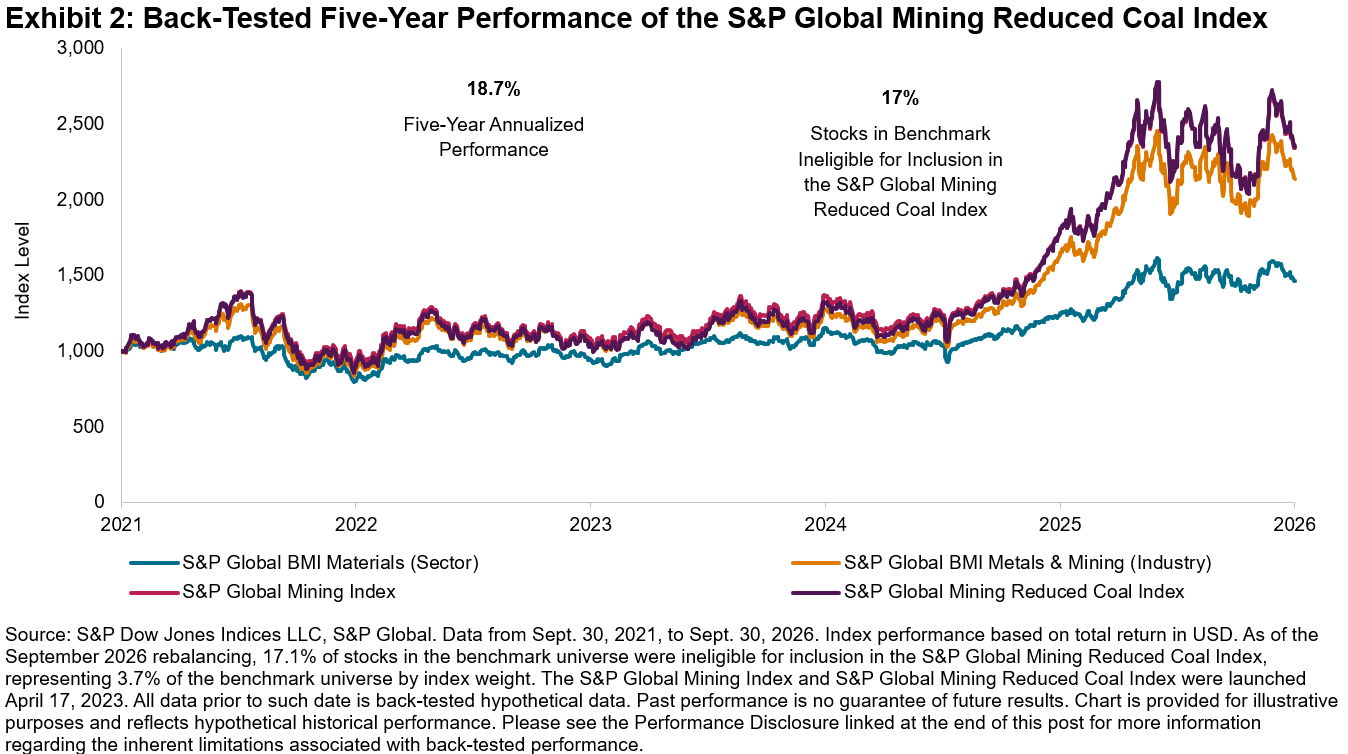
Exhibit 2 highlights the impact of this approach. Over the past five years, the S&P Global Mining Index has outperformed broader global mining and materials benchmarks, illustrating the historical benefit of focusing on companies with measurable mining activity.

Left Out in the Coal

Mining is essential to the modern economy, but its impacts warrant careful consideration. More broadly, there have been efforts to advance responsible mining practices. The S&P Global Mining Reduced Coal Index had a similar performance profile as the broader benchmarks, but with lower coal involvement, one of the sector’s more challenged commodities.

Make Mine a Double

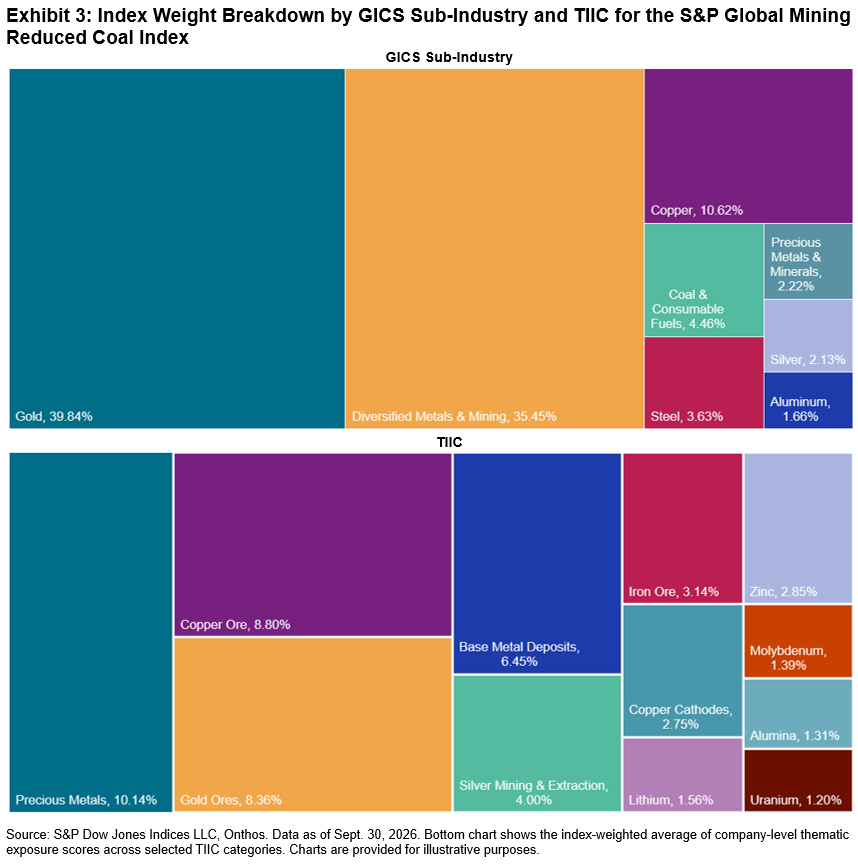
Mining exposure is rarely as straightforward as a single-metal label suggests. While investors may think of companies as “gold miners” or “copper miners,” the reality is that many businesses operate across multiple resources, geographies and projects, with fortunes linked to several resource trends.

Exhibit 3 digs into the index composition through both the GICS sub-industry framework and the Theia Insights Industry Classification (TIIC). Developed by Onthos (formerly Theia Insights), TIIC uses natural language processing to analyze company disclosures and identify the business activities driving company exposure on a one-to-many basis.

The Aura around Gold and Other Metals

Several metals have attracted increased investor attention in recent years, albeit for different reasons. Gold has benefited from demand for reserve assets, diversification and persistent geopolitical uncertainty. Silver (often a byproduct from mining other base metals) has occupied a unique position, supported by both its precious metal characteristics and its growing role in industrial applications, including solar technologies and electronics. Copper remains central to electrification, grid modernization and expanding data center infrastructure, with long-term demand expectations tied to both energy transition and digitalization themes.

The outlook for lithium has been more volatile, reflecting periods of rapid capacity expansion alongside strong long-term expectations for battery supply chains and energy storage. Meanwhile, uranium has experienced renewed interest as governments and utilities increasingly focus on energy security, power reliability and the potential role of nuclear generation in meeting future electricity demand. S&P Global research, including the 2026 Metals Price Outlook, highlights the growing strategic importance of these commodities as countries seek to secure critical mineral supply chains and support future infrastructure investment.

Stocking Up for Tomorrow

Many children (and adults alike) will be hoping for a shiny new gadget this Christmas. Few will be hoping to find coal in their stocking. The S&P Global Mining Reduced Coal Index has a little more shine and fewer coal stocks, with a focus on companies supplying many of the metals and minerals powering today’s and tomorrow’s economy.

1 Stocks must exhibit at least one of the positive criteria referenced for the prior fiscal year for any of the following metals: aluminum, chromium, coal, cobalt, copper, gold, graphite, iron ore, lanthanides, lead, lithium, manganese, molybdenum, nickel, palladium, platinum, silver, tin, titanium, uranium and zinc. For more information, please see the S&P Thematic Indices Methodology.

The posts on this blog are opinions, not advice. Please read our Disclaimers.
Greek Myths and Icelandic Sagas: Reclassifications in the Global Market Library

Contributor Image
Diego Zurita

Senior Analyst, Global Equities & Thematics

S&P Dow Jones Indices

On Sept. 21, 2026, two markets crossed important thresholds in the S&P Dow Jones Indices (S&P DJI) global equity benchmark. Greece finished an odyssey back to developed market status after a 12-year hiatus, while Iceland rose, saga-like, to emerging market status. In this blog, we look at the details of why these changes happened and their impact on the composition of global benchmarks.

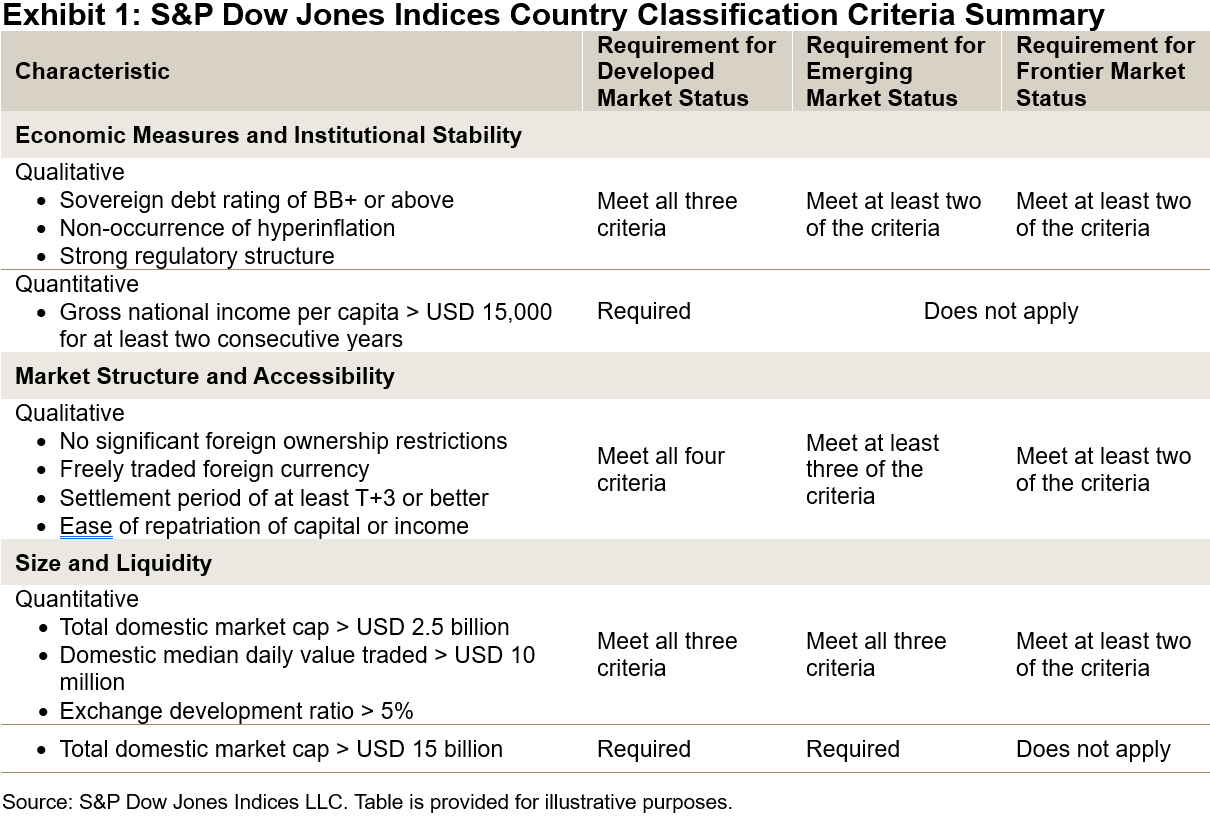
But first, how does S&P DJI decide how to classify a country? S&P DJI’s country classification framework1 relies on both quantitative and qualitative factors, as shown in Exhibit 1, as well as feedback from market participants. Based on these inputs, an index committee makes the final classification decision.

An Odyssey Home: Greece Returns to Developed Market Status

Before the Greek debt crisis, Greece was classified as a developed market. Amid the sovereign debt turmoil and long recession that followed, S&P DJI announced Greece’s move to emerging market status in 2013, with the change taking effect in September 2014. For over a decade, the country experienced significant socioeconomic challenges and hardships, including defaulting on an IMF payment,2 persistent high unemployment and rising poverty.3 By 2018, after a period of reforms and fiscal discipline, Greece secured a debt-relief agreement that began to change the country’s credit trajectory.4, 5 As of October 2025, the country held an S&P Global Rating of BBB/A-2 with a stable outlook,6 and the economy has resumed growth.7 Greece’s journey back to developed market status was nothing short of an odyssey.

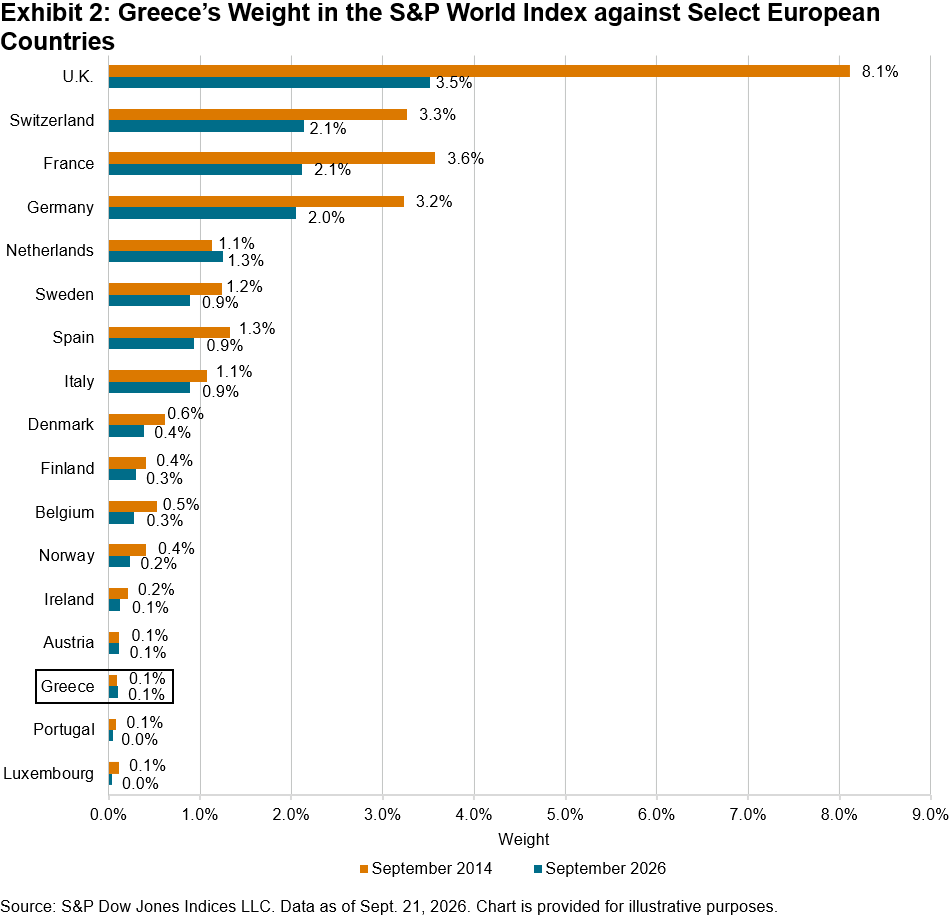
Greece joined S&P DJI’s developed market benchmarks in September 2026. The country is now part of the S&P World Index, accounting for a weight of about 0.1%, not too different than the weight it had before its reclassification to emerging market status (see Exhibit 2). However, the stock market has changed. As of the September 2026 rebalance, the float-adjusted market capitalization (FMC) of the S&P Greece BMI was USD 110.8 billion, compared to USD 29.1 billion before being moved to emerging markets. The number of constituents also grew, from having 20 stocks across 7 GICS® sectors to including 51 stocks across 10 GICS sectors. Notably, the weight of the Financials sector increased from 31.5% to 49.3%, while the weight of the Consumer Discretionary and Communication Services sectors decreased from 19.8% to 4.0% and from 11.0% to 3.3%, respectively.

After the Economic Ragnarök: A Frontier No More

While Greece’s odyssey was rooted in a sovereign debt crisis, Iceland’s story began with a very different kind of financial collapse. Just weeks after Lehman Brothers declared bankruptcy in 2008, a wholesale funding refinancing failure and run of foreign-currency deposits triggered the collapse of all three major Icelandic banks. These banks were unsustainably large, holding assets equivalent to more than 10 times the size of the country’s GDP, mostly denominated in foreign currency.8 Through an IMF bailout, austerity, capital controls and banking reforms, the country managed to resolve the crisis.9 Iceland has since lifted capital controls10 and, since October 2025, has held an A+/A-1 rating from S&P Global Ratings with a stable outlook.11 While its stable economy has benefited from a rebound in tourism12 and, as of September 2025, more than one-half of the FMC of its stock market came from the Financials sector, policymakers are pushing to diversify the economy.13 Just as Norse mythology tells of a new world born from the ashes of Ragnarök, Iceland’s economy had a rebirth and just recently received an upgraded classification after meeting the required criteria.

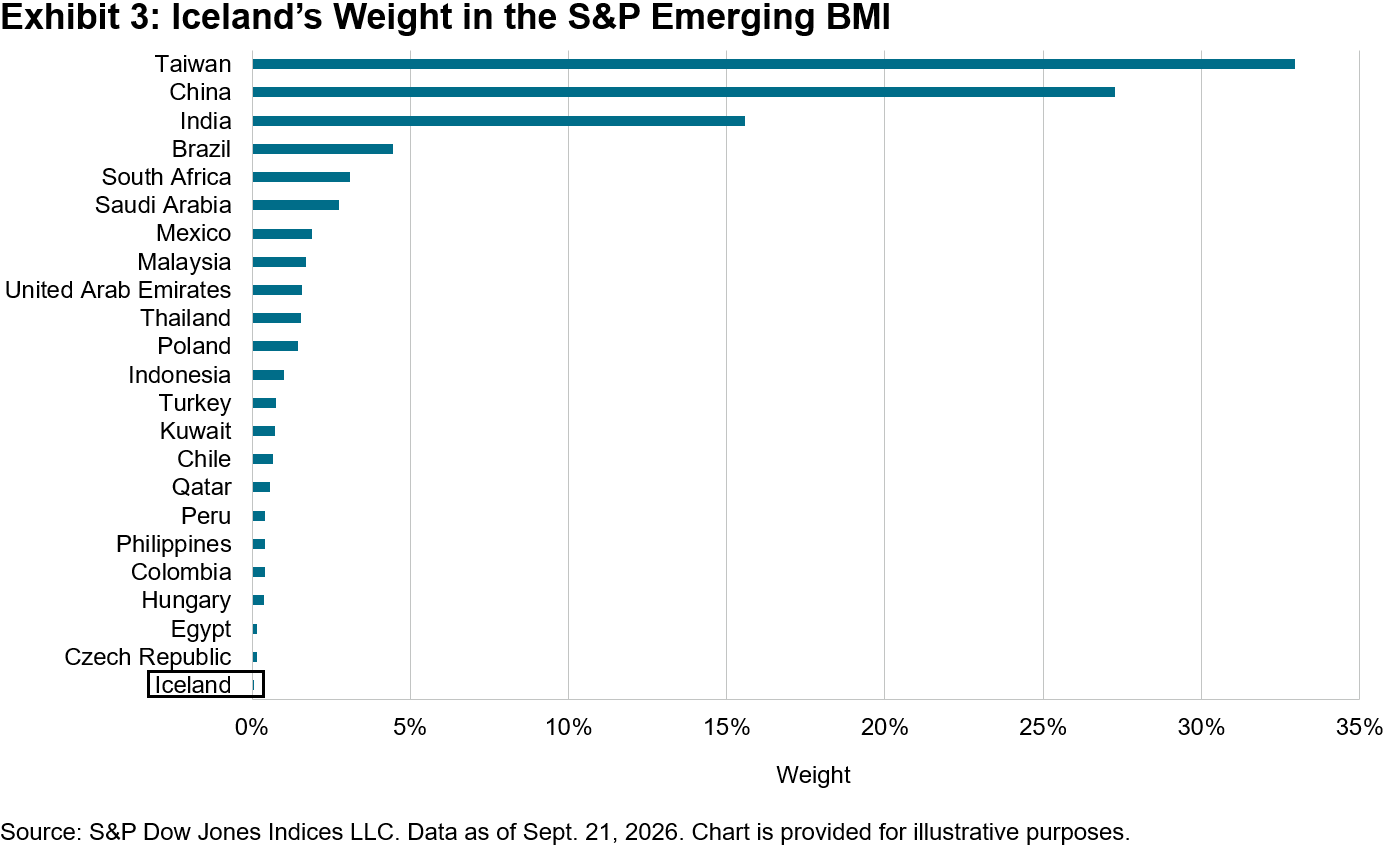
Previously classified as a frontier market, Iceland has now joined emerging market benchmarks. As of Sept. 21, 2026, the S&P Iceland BMI included 12 stocks across 7 GICS sectors, with an FMC of USD 9.5 billion. At initial inclusion, the country was the smallest constituent of the S&P Emerging BMI, with a weight of 0.07% (see Exhibit 3).

Though these countries hold modest weight, their new status changes the investor base tracking them. The tales of Greece and Iceland illustrate the dynamic nature of market classifications. Developments around a country’s economic health, market infrastructure and accessibility can lead to a reclassification in the global market library.

1 See the S&P Dow Jones Indices Country Classification Methodology for more information.

2 “Greece debt crisis: IMF payment missed as bailout expires,” BBC, July 1, 2015.

3 Rodgers, Lucy and Nassos Stylianou, “How bad are things for the people of Greece?” BBC, July 16, 2015.

4 “Greece hails ‘historic’ debt relief deal,” BBC, June 22, 2018.

5 Hatzidakis, Konstantinos, “Greece’s Remarkable Recovery,” IMF, June 2025.

6 “Greece Affirmed At ‘BBB/A-2’; Outlook Stable,” S&P Global Ratings, Oct. 17, 2025.

7 “Economic forecast for Greece,” European Commission, May 21, 2026.

8 Baudino, Patrizia, Jon Thor Sturluson and Jean-Philippe Svoronos, “The banking crisis in Iceland,” Bank for International Settlements, March 2020.

9 Tranøy, Bent Sofus and Throstur Olaf Sigurjonsson, “Back from the Brink: Iceland’s Successful Economic Recovery,” Successful Public Policy in the Nordic Countries: Cases, Lessons, Challenges, Oct. 20, 2022.

10 “Iceland ends capital controls after more than eight years of restrictions,” Reuters, March 12, 2017.

11 “Iceland ‘A+/A-1’ Ratings Affirmed; Outlook Stable,” S&P Global Ratings, Sept. 5, 2025.

12 “OECD Economic Surveys: Iceland 2025,” OECD, June 26, 2025.

13 “Industrial Policy – A Growth Plan to 2035,” Prime Minister’s Office, Iceland, April 2026.

The posts on this blog are opinions, not advice. Please read our Disclaimers.