

Lumps of coal are typically reserved for the Christmas stocking of the worst-behaved children. With the holiday season approaching, many will be hoping instead for something a little shinier and more refined.
The S&P Global Mining Reduced Coal Index follows a similar philosophy. Start with a universe of mining-related companies. Focus on those with meaningful involvement in metals and minerals. Remove companies with significant coal exposure. What remains is a more targeted set of businesses involved in extracting some of the resources shaping the economy, from gold and silver to copper, lithium and uranium.
Reinforcing Positive Behavior
The starting point is the S&P Global Mining Index, which leverages commodity-level intelligence from S&P Global Energy (formerly S&P Global Commodity Insights). Eligibility is determined through evidence of positive global production value, sales volume, royalty revenue or reserves linked to a defined basket of mined commodities.1
This activity screen acts as a quality filter, recognizing multiple forms of meaningful participation (see Exhibit 1). Companies generating production value or sales volumes are actively participating in resource extraction today, while royalty companies provide financing and exposure to the underlying economics of mining projects. Reserves, meanwhile, provide evidence of resource ownership and future production potential. Collectively, these measures focus the index on companies with demonstrable involvement in the mining value chain rather than speculative exploration activity.
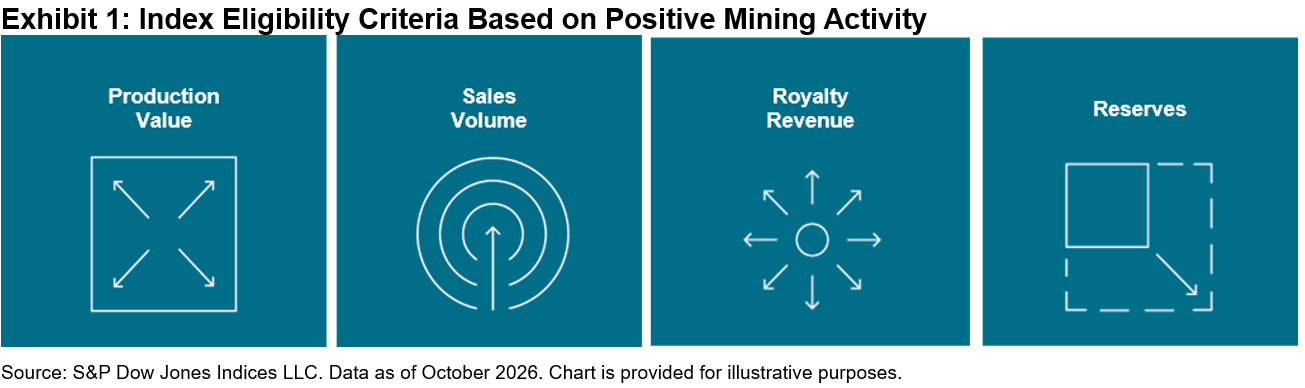
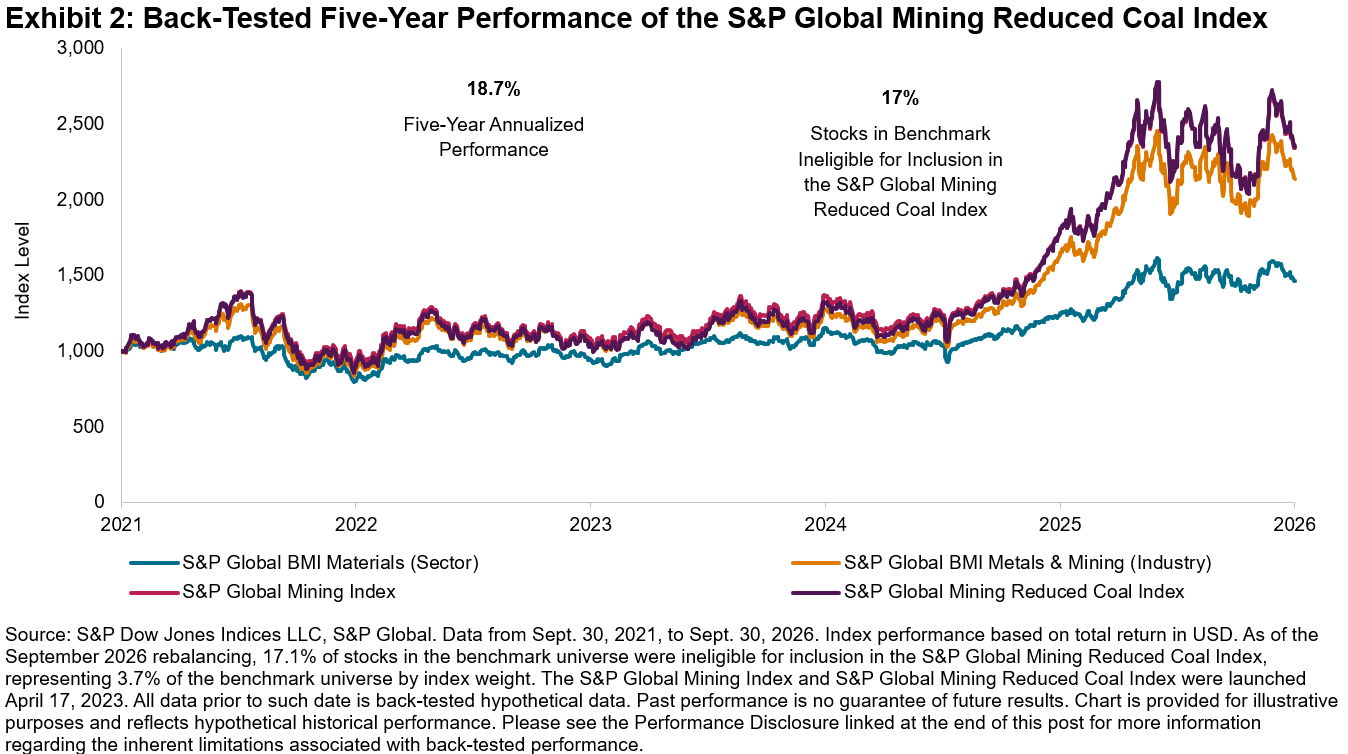
Exhibit 2 highlights the impact of this approach. Over the past five years, the S&P Global Mining Index has outperformed broader global mining and materials benchmarks, illustrating the historical benefit of focusing on companies with measurable mining activity.
Left Out in the Coal
Mining is essential to the modern economy, but its impacts warrant careful consideration. More broadly, there have been efforts to advance responsible mining practices. The S&P Global Mining Reduced Coal Index had a similar performance profile as the broader benchmarks, but with lower coal involvement, one of the sector’s more challenged commodities.
Make Mine a Double
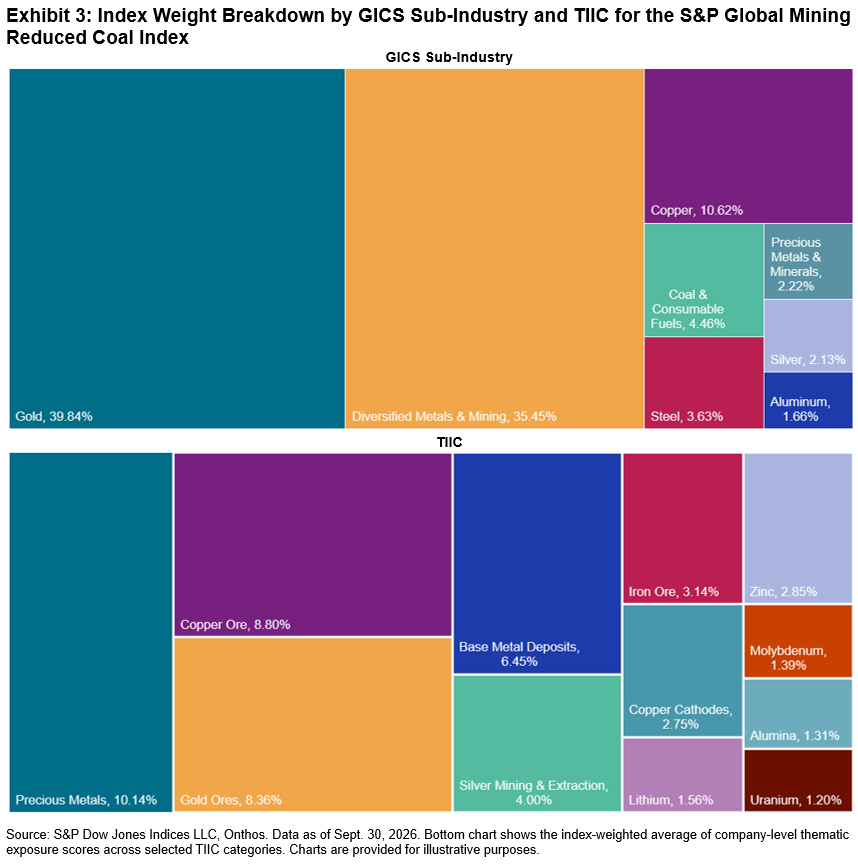
Mining exposure is rarely as straightforward as a single-metal label suggests. While investors may think of companies as “gold miners” or “copper miners,” the reality is that many businesses operate across multiple resources, geographies and projects, with fortunes linked to several resource trends.
Exhibit 3 digs into the index composition through both the GICS sub-industry framework and the Theia Insights Industry Classification (TIIC). Developed by Onthos (formerly Theia Insights), TIIC uses natural language processing to analyze company disclosures and identify the business activities driving company exposure on a one-to-many basis.
The Aura around Gold and Other Metals
Several metals have attracted increased investor attention in recent years, albeit for different reasons. Gold has benefited from demand for reserve assets, diversification and persistent geopolitical uncertainty. Silver (often a byproduct from mining other base metals) has occupied a unique position, supported by both its precious metal characteristics and its growing role in industrial applications, including solar technologies and electronics. Copper remains central to electrification, grid modernization and expanding data center infrastructure, with long-term demand expectations tied to both energy transition and digitalization themes.
The outlook for lithium has been more volatile, reflecting periods of rapid capacity expansion alongside strong long-term expectations for battery supply chains and energy storage. Meanwhile, uranium has experienced renewed interest as governments and utilities increasingly focus on energy security, power reliability and the potential role of nuclear generation in meeting future electricity demand. S&P Global research, including the 2026 Metals Price Outlook, highlights the growing strategic importance of these commodities as countries seek to secure critical mineral supply chains and support future infrastructure investment.
Stocking Up for Tomorrow
Many children (and adults alike) will be hoping for a shiny new gadget this Christmas. Few will be hoping to find coal in their stocking. The S&P Global Mining Reduced Coal Index has a little more shine and fewer coal stocks, with a focus on companies supplying many of the metals and minerals powering today’s and tomorrow’s economy.
1 Stocks must exhibit at least one of the positive criteria referenced for the prior fiscal year for any of the following metals: aluminum, chromium, coal, cobalt, copper, gold, graphite, iron ore, lanthanides, lead, lithium, manganese, molybdenum, nickel, palladium, platinum, silver, tin, titanium, uranium and zinc. For more information, please see the S&P Thematic Indices Methodology.
The posts on this blog are opinions, not advice. Please read our Disclaimers.