

In Homer’s Odyssey, the title character, Odysseus, spends years away from home fighting at Troy before making the challenging journey home to Ithaca. Sirens tempt him off course, lotus flowers cause his sailors to lose sight of their objective and storms repeatedly delay the voyage. The clean energy industry has faced its own odyssey: a long transition shaped by changing priorities, policy turns and geopolitical disruption.
The S&P Global Clean Energy Transition Index has served as a compass throughout this journey. Launched in 2007, almost 20 years ago, it measures the performance of companies involved in clean energy-related businesses, spanning power generation and enabling technologies. Its history covers periods of market enthusiasm and retrenchment; it peaked in 2008, then declined over an extended period before rising again during the COVID-19 pandemic. Since 2021, the index has been rewired for greater transparency, expanded emerging markets coverage and stricter carbon reduction requirements.
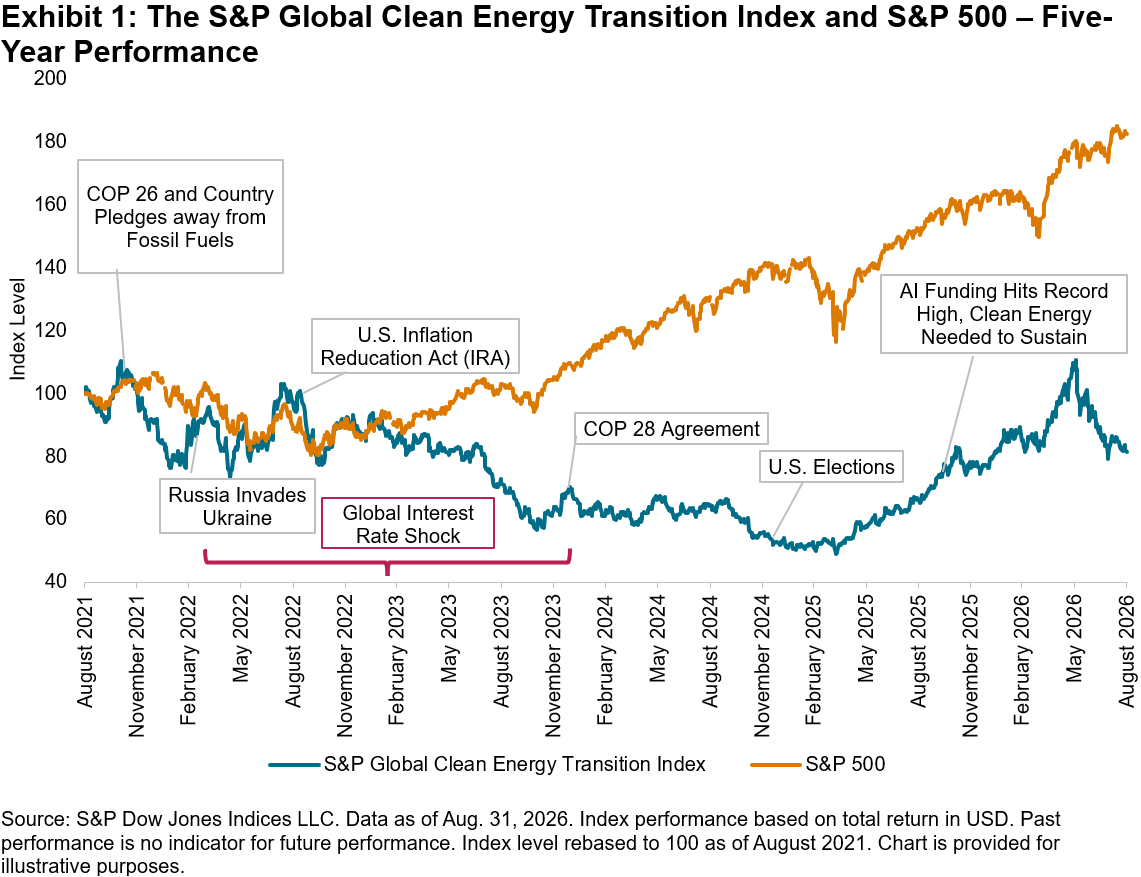
Exhibit 1 illustrates its ongoing, choppy journey since then. Over the five-year period ending Aug. 31, 2026, the S&P Global Clean Energy Transition Index declined 4.1%, compared with a 12.8% gain for the S&P 500®. Higher interest rates created storms; shifting policy priorities acted like lotus flowers, pulling focus away from renewables back to fossil fuels; wars and geopolitical tensions posed obstacles; and the rise of artificial intelligence (AI) emerged as a new siren, commanding investor attention while also creating fresh opportunities for clean energy.
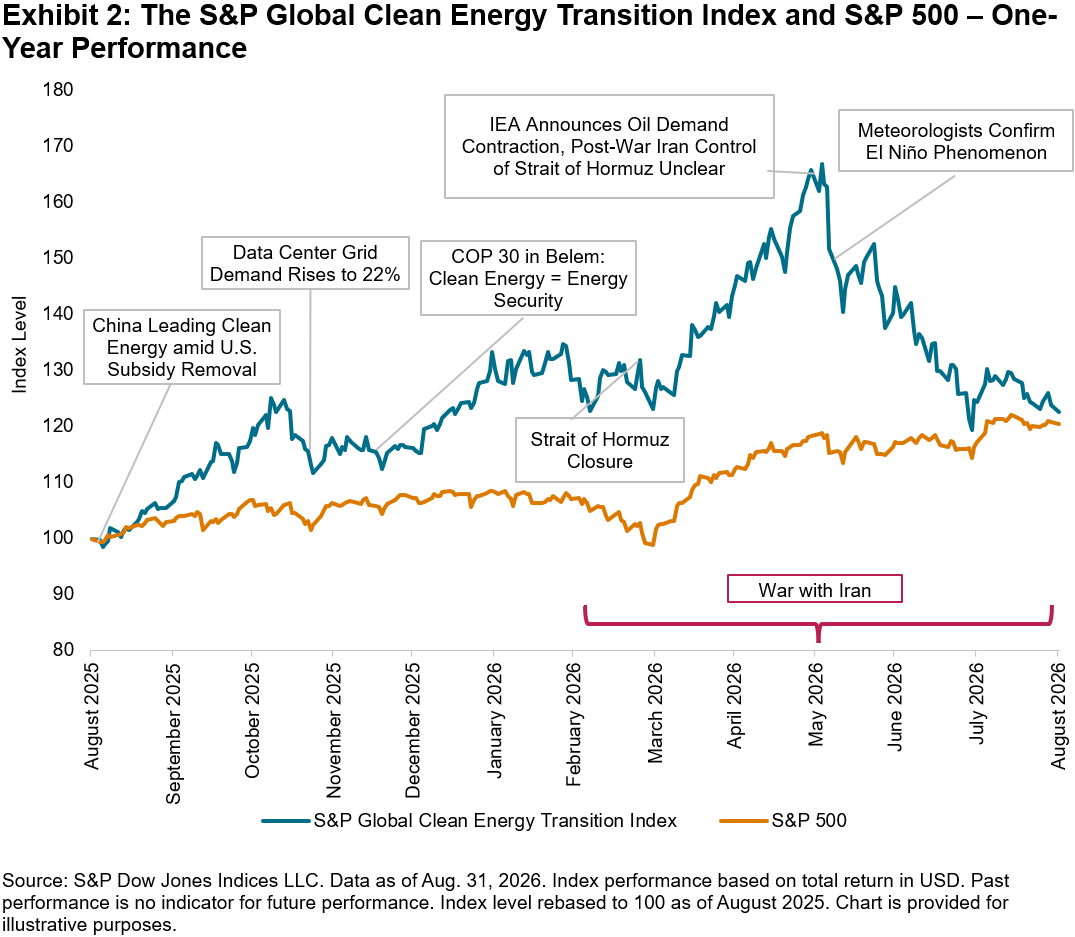
The one-year performance as seen in Exhibit 2 reflects the latter part of the tale. The S&P Global Clean Energy Transition Index gained 22.65% in the one-year period ending Aug. 31, 2026, outperforming the S&P 500. The war in the Middle East reinforced the importance of diversified energy sources and reduced dependence on geopolitically sensitive regions. In the U.S., the accelerated phaseout of key clean energy incentives compressed project timelines, prompting developers to rush to secure eligibility for their projects rather than causing an immediate slowdown in deployment. At the same time, clean energy is becoming a cornerstone in meeting AI’s growing hunger for power. Solar and energy storage are increasingly at the center of that buildout, with hyperscalers signing gigawatt-scale power agreements to secure the electricity needed for expanding data center infrastructure.
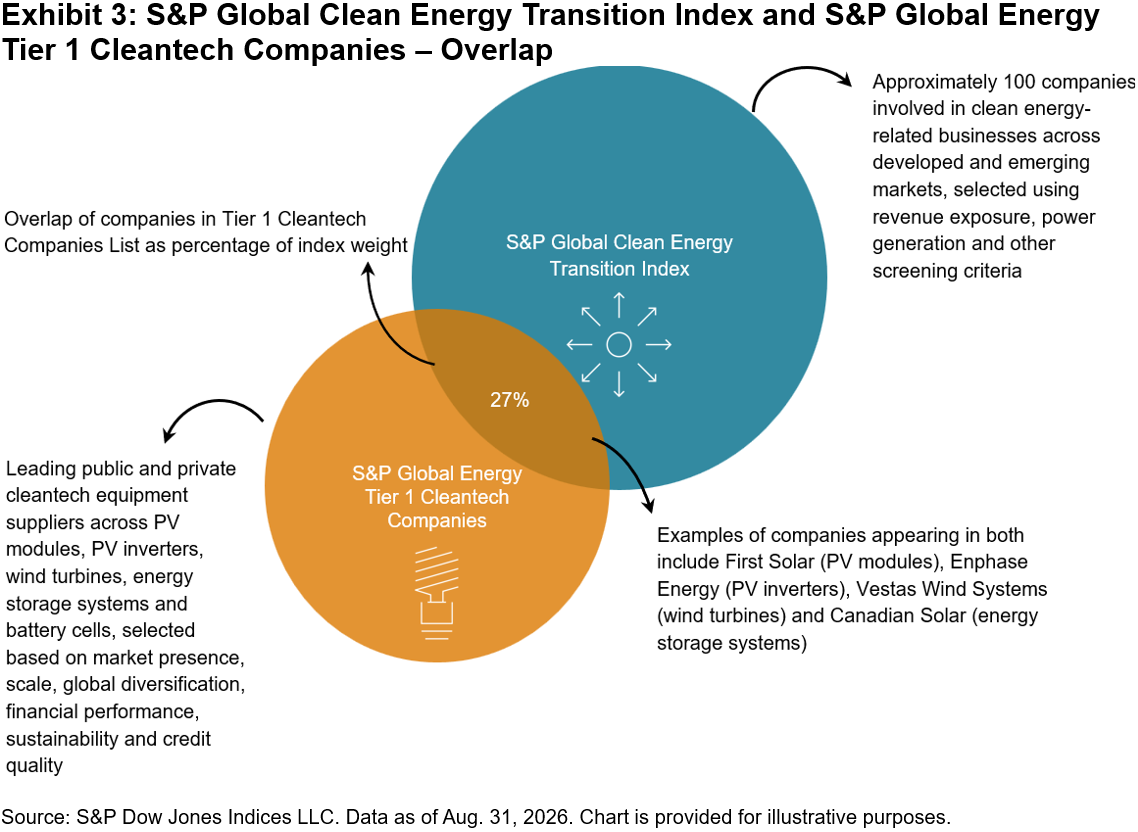
The maturity in the theme and industry is also reflected in S&P Global Energy’s Tier 1 Cleantech Companies List, bringing the focus back to the need for resilient infrastructure. Covering photovoltaic (PV) modules, PV inverters, wind turbines, energy storage systems and battery cells, the list identifies companies that meet rigorous criteria spanning market presence, scale, global diversification, financial performance, sustainability and credit risk.
While the two universes serve different purposes—with the S&P Global Clean Energy Transition Index encompassing a broad range of clean energy activities and the Tier 1 Cleantech Companies List focusing on leading equipment suppliers across both public and private markets—there is notable overlap between them (see Exhibit 3). As the energy transition matures, supplier quality, operational resilience and long-term durability are becoming important components of clean energy system readiness.
The challenge is no longer simply adding renewable capacity; clean energy investment now exceeds fossil fuel equivalent by nearly 2 to 1, a gap that has widened over the past decade.1 Increasingly, what matters is converting generation into reliable, deliverable power through grid connections, permitting, storage, supportive regulation and suppliers capable of servicing equipment over an asset’s life. The clean energy investment case is expanding beyond clean generation to encompass the infrastructure nexus and need to produce, transmit, store and manage electricity.
Odysseus eventually reached home, but only after navigating Poseidon’s high seas. Unlike our hero, the clean energy industry does not have the luxury of divine guidance. Its next course will depend on resilience beyond power generation alone. Climate variability, including the potential for a strong El Niño, may increase the risk of heat, drought, flooding and wildfire, placing pressure on grids, water systems and supply chains. What the weather gods have in store remains uncertain; the S&P Global Clean Energy Transition Index and S&P Global Energy Tier 1 Cleantech Companies List offer a window into the companies helping build the raft for the journey ahead.
1 See Forbes, “Clean Energy Is Outspending Fossil Fuekindlls Nearly Two To One,” June 7, 2026.
The posts on this blog are opinions, not advice. Please read our Disclaimers.