

The S&P 500® fell 1% in October and dropped by 4% on Nov. 5, 2026, its worst day since April 2025, as AI-related worries weighed on tech stocks.1 Smaller caps have offered a refuge: in October, the S&P MidCap 400 and S&P SmallCap 600 outperformed the 500 by 3% and 4%, respectively.
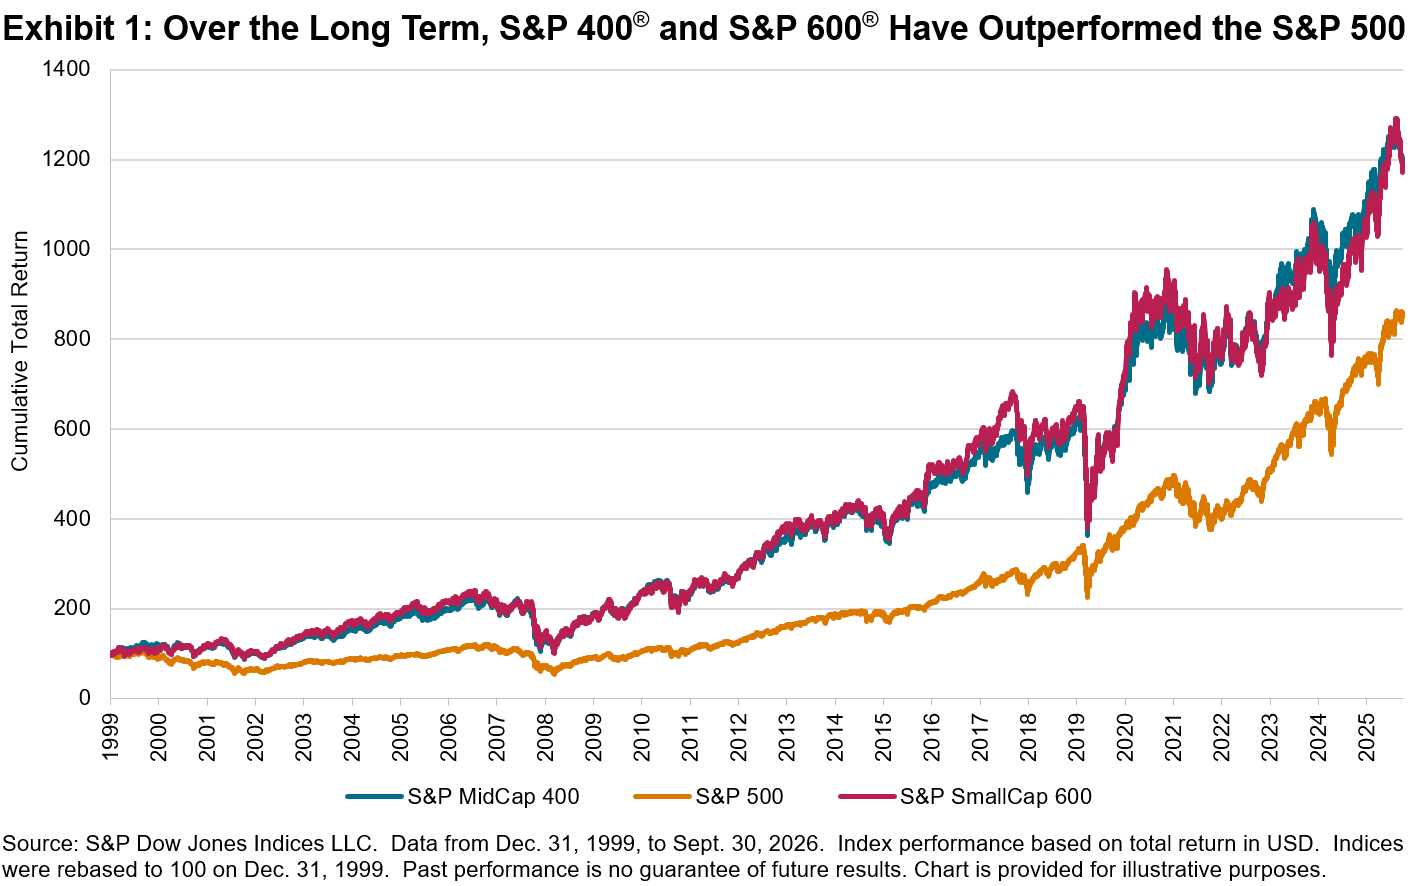
Mega-cap stocks have dominated headlines, but historically, smaller companies have had an outsized impact on market returns. In particular, the S&P MidCap 400 and the S&P SmallCap 600 outperformed the S&P 500 over the past quarter century.2
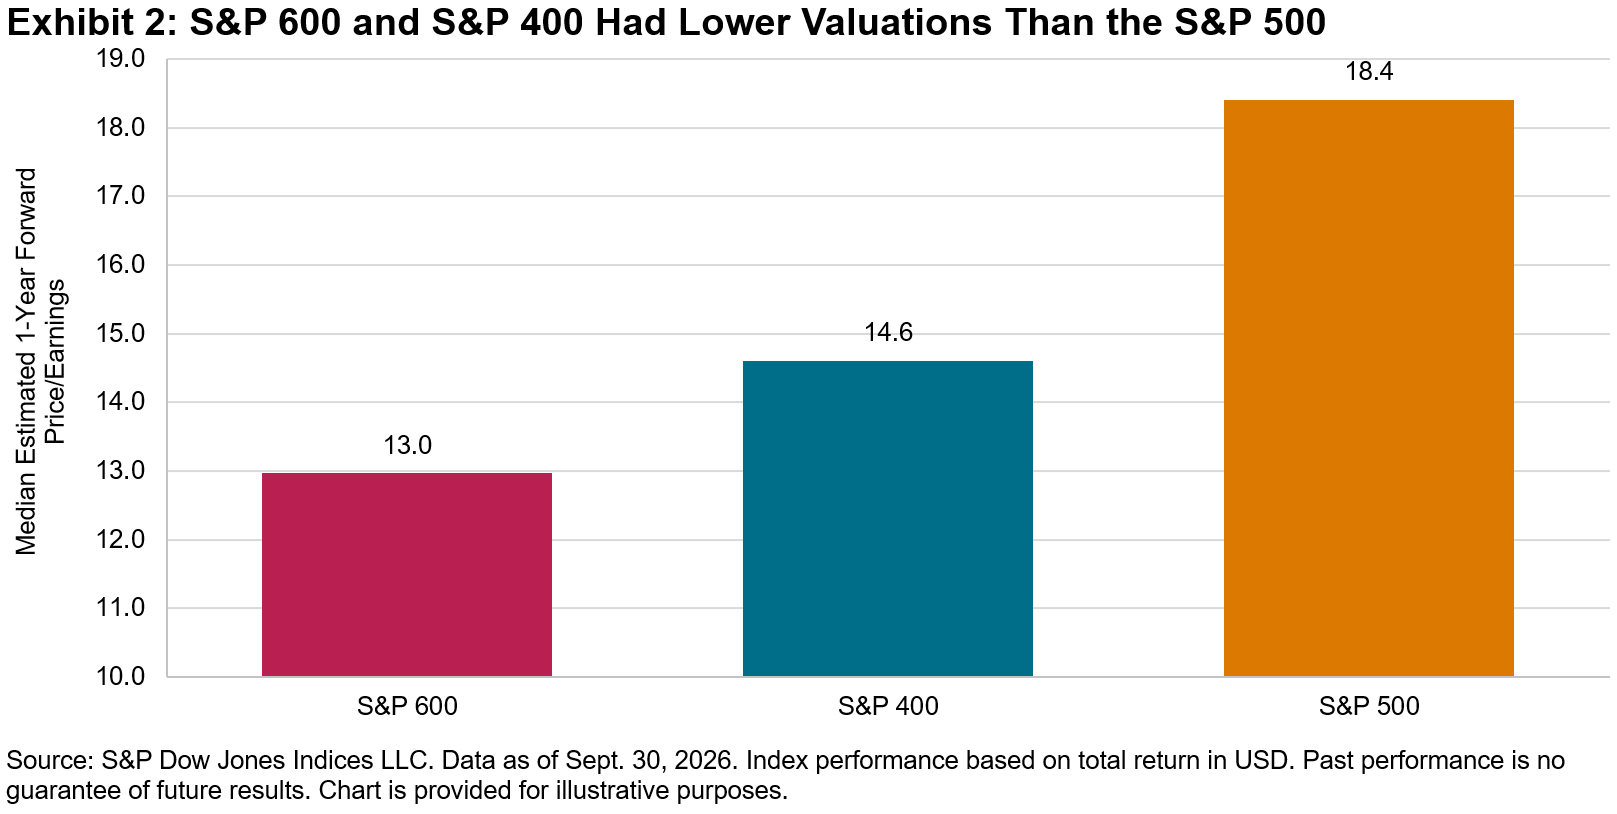
One mechanism that may help explain why small caps have tended to outperform larges caps is their value tilt, as small caps have typically traded at lower valuations than large caps.3 Exhibit 2 shows that, as of Sept. 30, 2026, the S&P 600 and S&P 400 traded at forward price-to-earnings (P/E) ratios of 13.0 and 14.6, respectively, compared to a forward P/E of 18.4 for the S&P 500.4
By combining the S&P 500 with the S&P MidCap 400 and the S&P SmallCap 600, the S&P Composite 1500® encompasses larger and smaller stocks, offering a more comprehensive view of the domestic stock market. Notably, the S&P Composite 1500 covers more than 95% of the cumulative U.S. equity market capitalization,5 as proxied by the S&P Total Market Index.
This inclusion of smaller companies has meant that the S&P 1500™ has outperformed the S&P 500 over the long term.6 However, the outperformance of the index as a whole does not necessarily extend to the performance of the component stocks in the index. For example, 70% of companies within the S&P 1500 underperformed the index in 2025.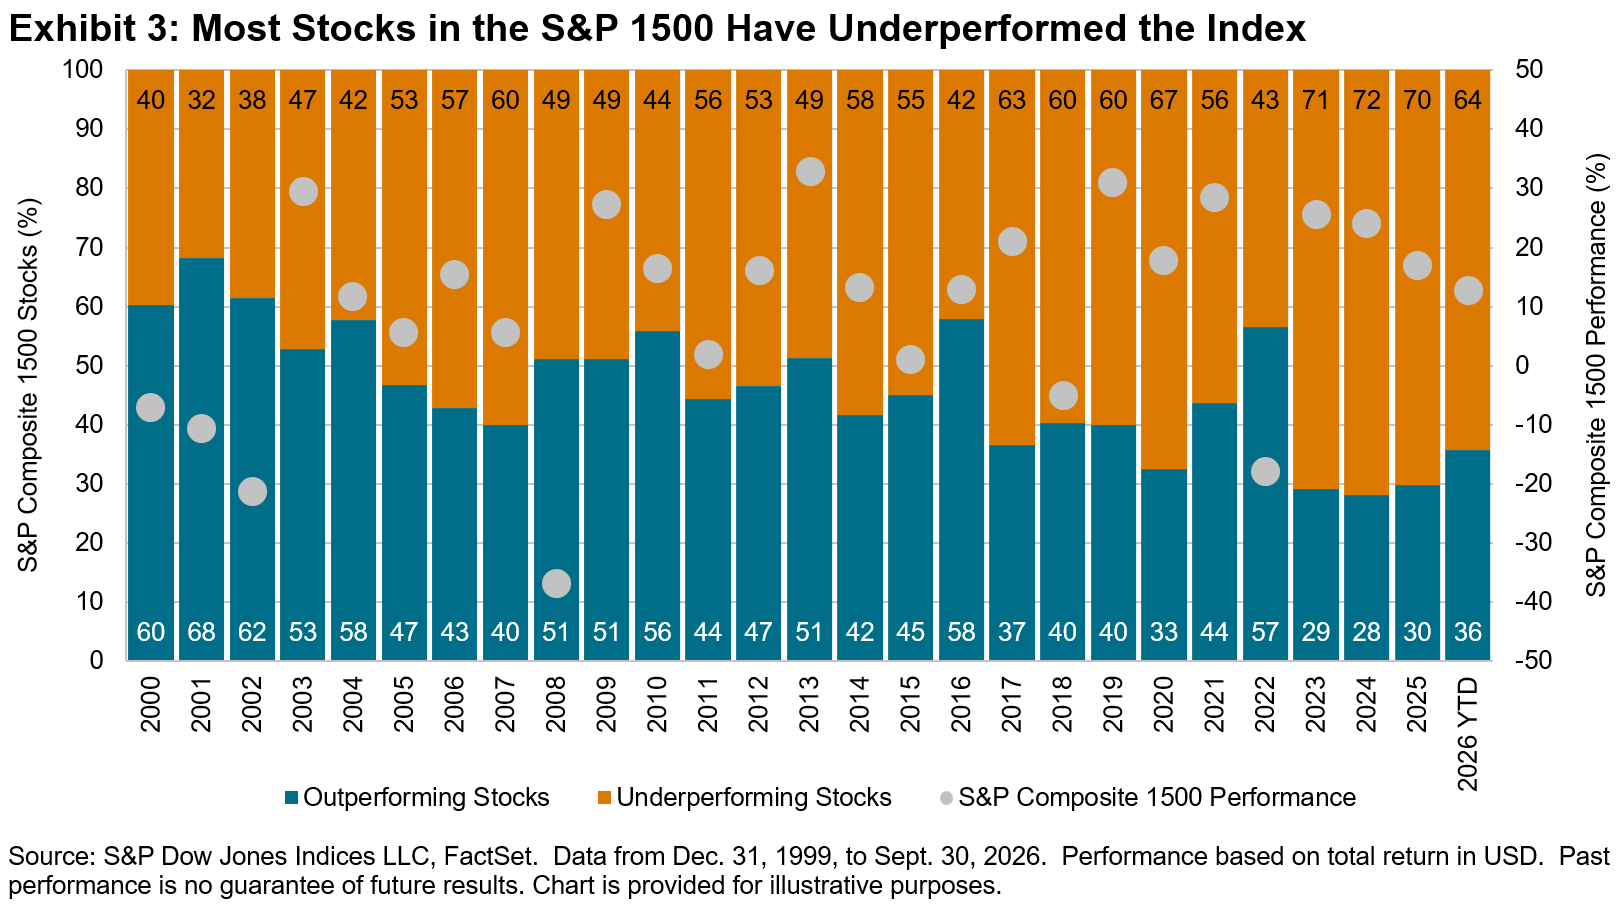
The minority of outperforming stocks is evidence of the positive skew seen in equity returns,7 with the average return exceeding the median. This skew highlights a possible benefit of indexing over active stock selection, since when fewer stocks outperform, active management tends to be more difficult.
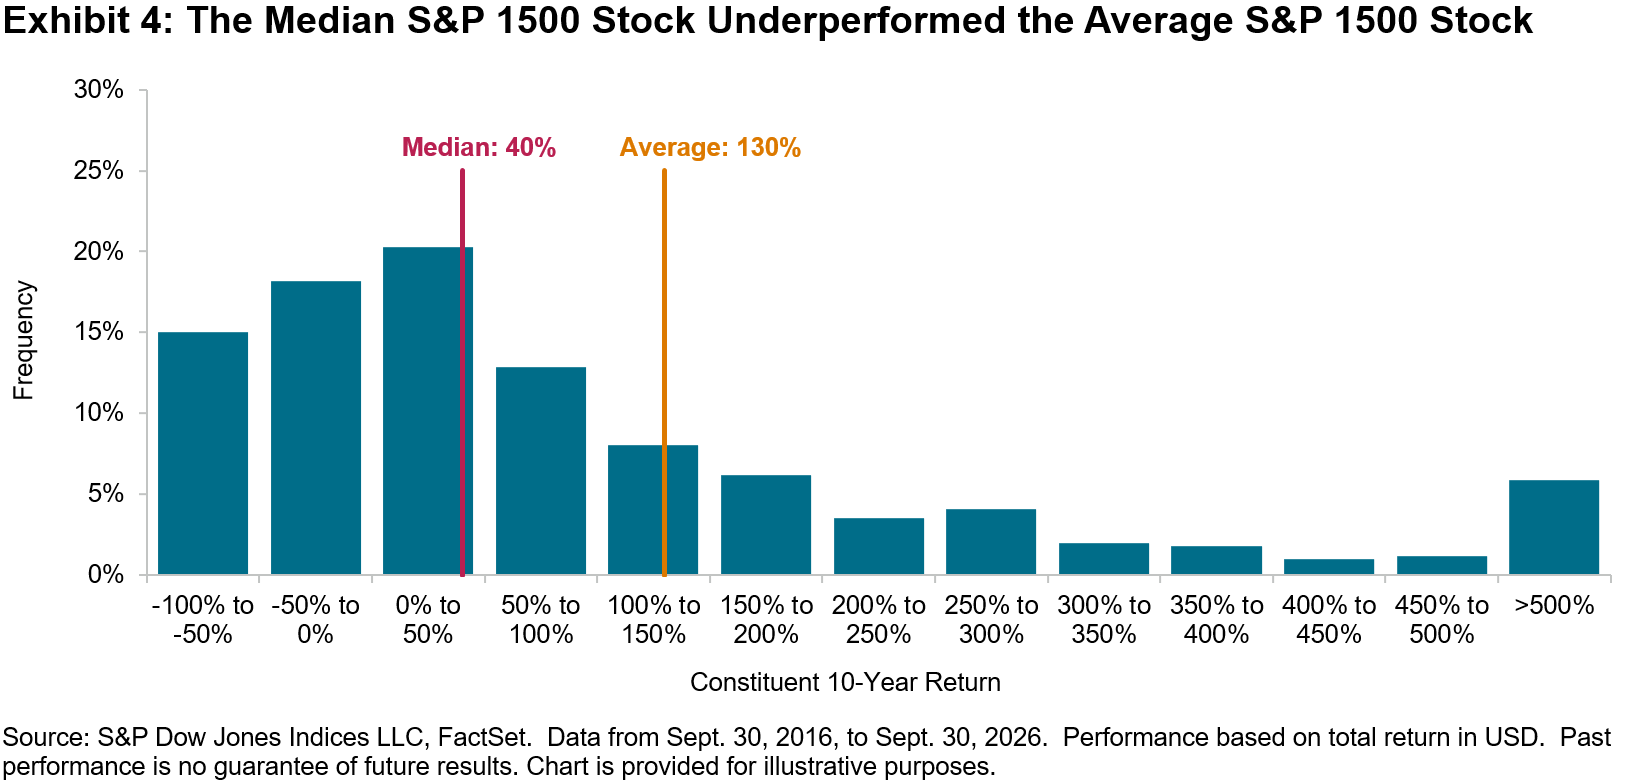
The S&P Composite 1500 brings together companies from across the U.S. equity market, combining the size and stability of large-cap companies with the growth potential of mid- and small-cap stocks. As empirical evidence underscores the challenge of identifying tomorrow’s winners through individual stock selection,8 this index can provide a simple and diversified way to measure the breadth of the U.S. market.
1 Ganti, Anu. “AI Anxiety or Opportunity.” S&P Dow Jones Indices LLC. Oct. 28, 2026.
2 Brzenk, Phillip and Hamish Preston. “The S&P Composite 1500: An Efficient Measure of the U.S. Equity Market.” S&P Dow Jones Indices LLC. May 28, 2020.
3 Fama, Eugene F., and Kenneth R. French. “Common Risk Factors in the Returns on Stocks and Bonds.” Journal of Financial Economics Volume 33, Issue 1, 1993, Pages 3-56.
4 Edwards, Tim and Sherifa Issifu. “Hidden in Plain Sight: U.S. Equities Beyond the S&P 500®.” S&P Dow Jones Indices LLC. April 13, 2021.
5 Preston, Hamish. “Celebrating 30 Years of the S&P Composite 1500.” S&P Dow Jones Indices LLC. May 19, 2025.
6 8.5% annualized total return for the S&P 1500 versus 8.3% for the S&P 500, from Dec. 31, 1999, to Sept. 30, 2026
7 Ganti, Anu. “Skewing Success.” S&P Dow Jones Indices LLC. Sept. 30, 2025.
8 For more information, please see our SPIVA® U.S. Mid-Year 2026 Scorecard. Note that more than 90% of funds in the All Domestic Funds Category underperformed the S&P Composite 1500 over trailing time periods longer than five years.
The posts on this blog are opinions, not advice. Please read our Disclaimers.